The Property Perfectionist™ | October 2026 | Chislehurst
A forensic look at buyer demand, time on market, price reductions and the Chislehurst properties that actually attracted offers.
33 homes came onto the BR7 market in October. Just one of those October launches had secured an offer before the month ended.
And yet 24 BR7 properties went under offer during October. That sounds like a contradiction until you look at when those properties first came onto the market.
I have been investigating the October figures for Chislehurst and Elmstead, looking at property types, asking price bands, marketing time, price reductions and the homes buyers actually chose. Here are the findings I would want to know if I were currently selling a home in BR7.
October at a glance
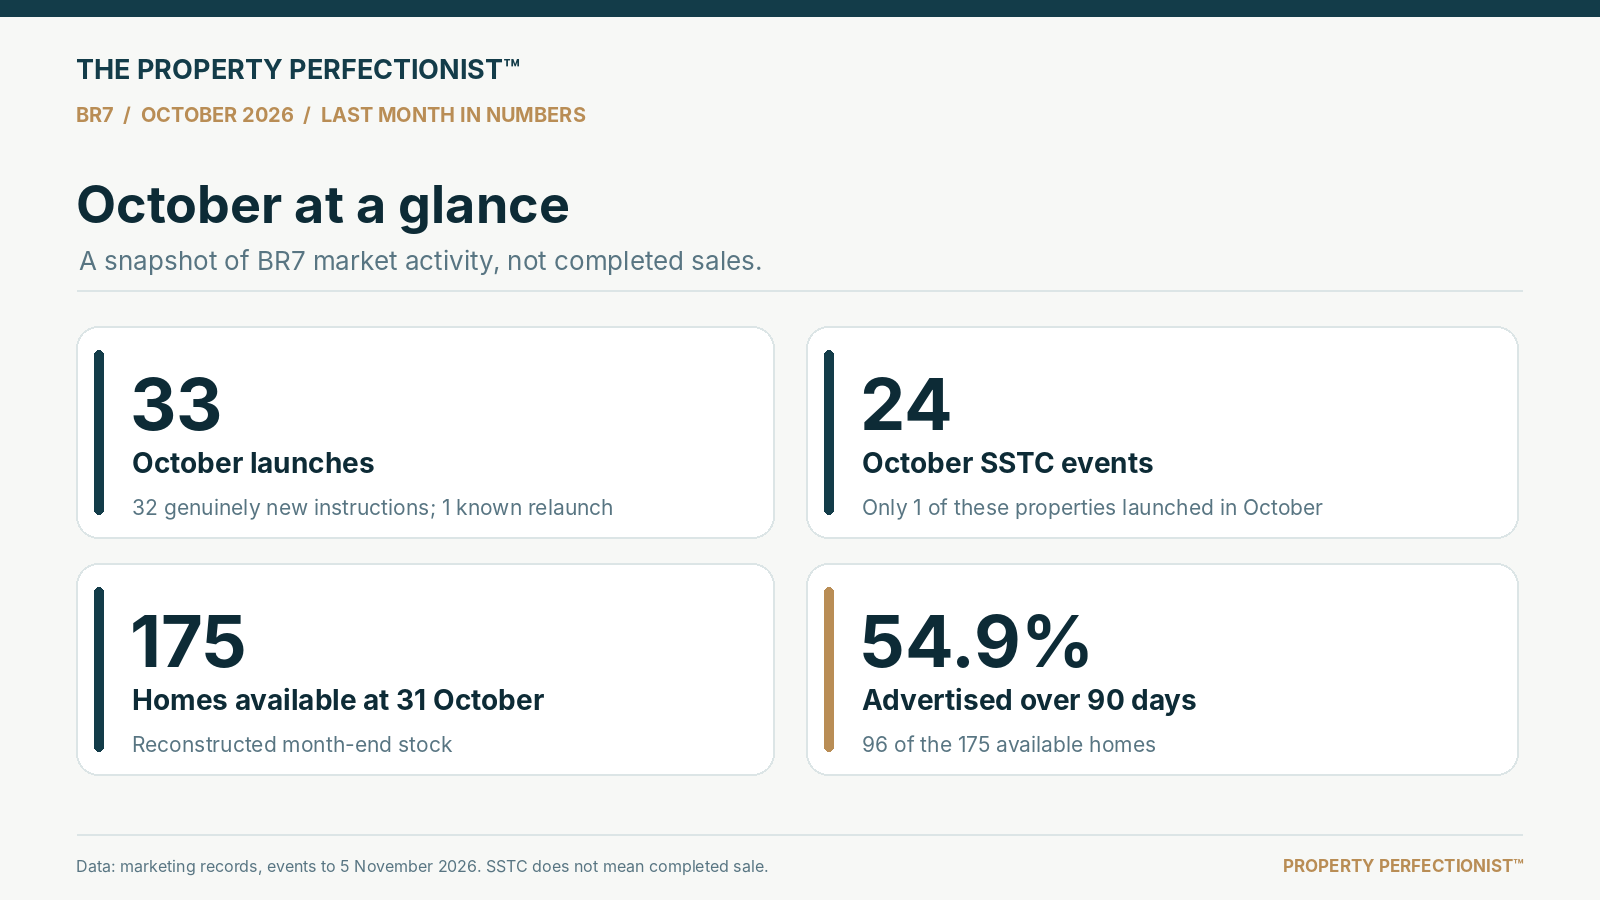
October 2026 activity. The under offer total covers properties launched in different months.
The first clue: October’s sales did not come from October’s launches
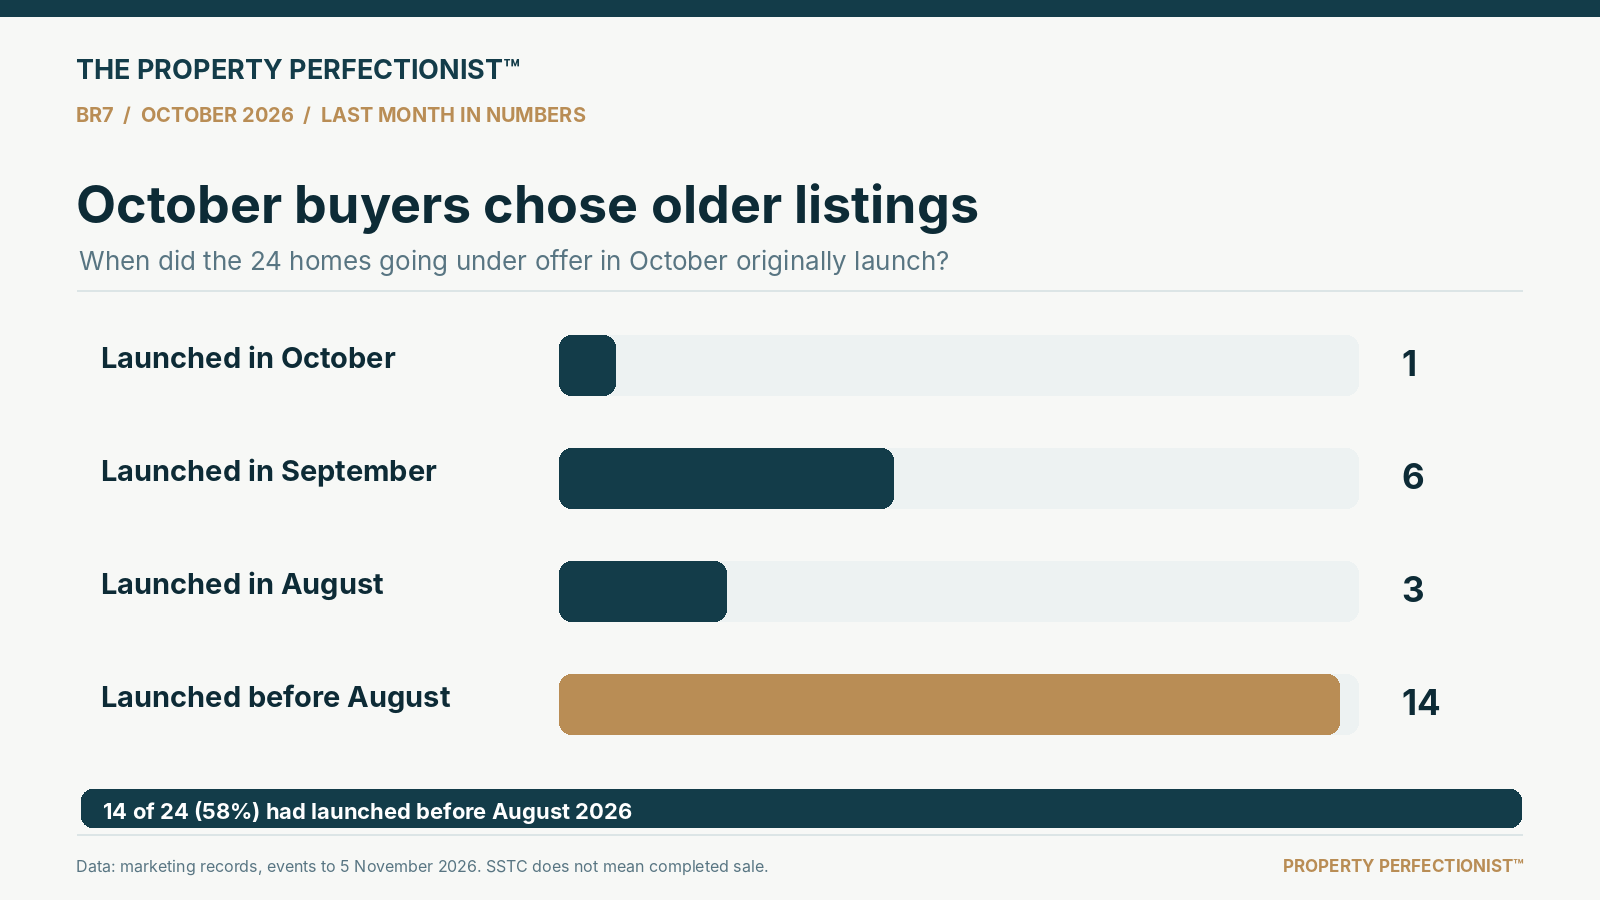
The largest group securing offers in October had been marketed since before August.
33 properties were advertised with an October launch date. Of these, 32 were genuine new instructions and one was a known relaunch. Just one of the 33 became sold subject to contract (SSTC) during October, equal to 3.0% of that launch group by 31 October.
At the same time, 24 homes went under offer. Twenty three had been marketed before October. Fourteen of the 24 had been launched before August, and those older homes had taken a median 187 days to attract an agreement.
That distinction matters. An October SSTC is an event that occurred during October, not necessarily a sale of a home first listed in October. And the 3.0% figure is a month end snapshot, not a prediction of how many October launches will ultimately sell. A home launched on 30 October had just two days to find a buyer before the month closed.
Four property types. Four different markets.
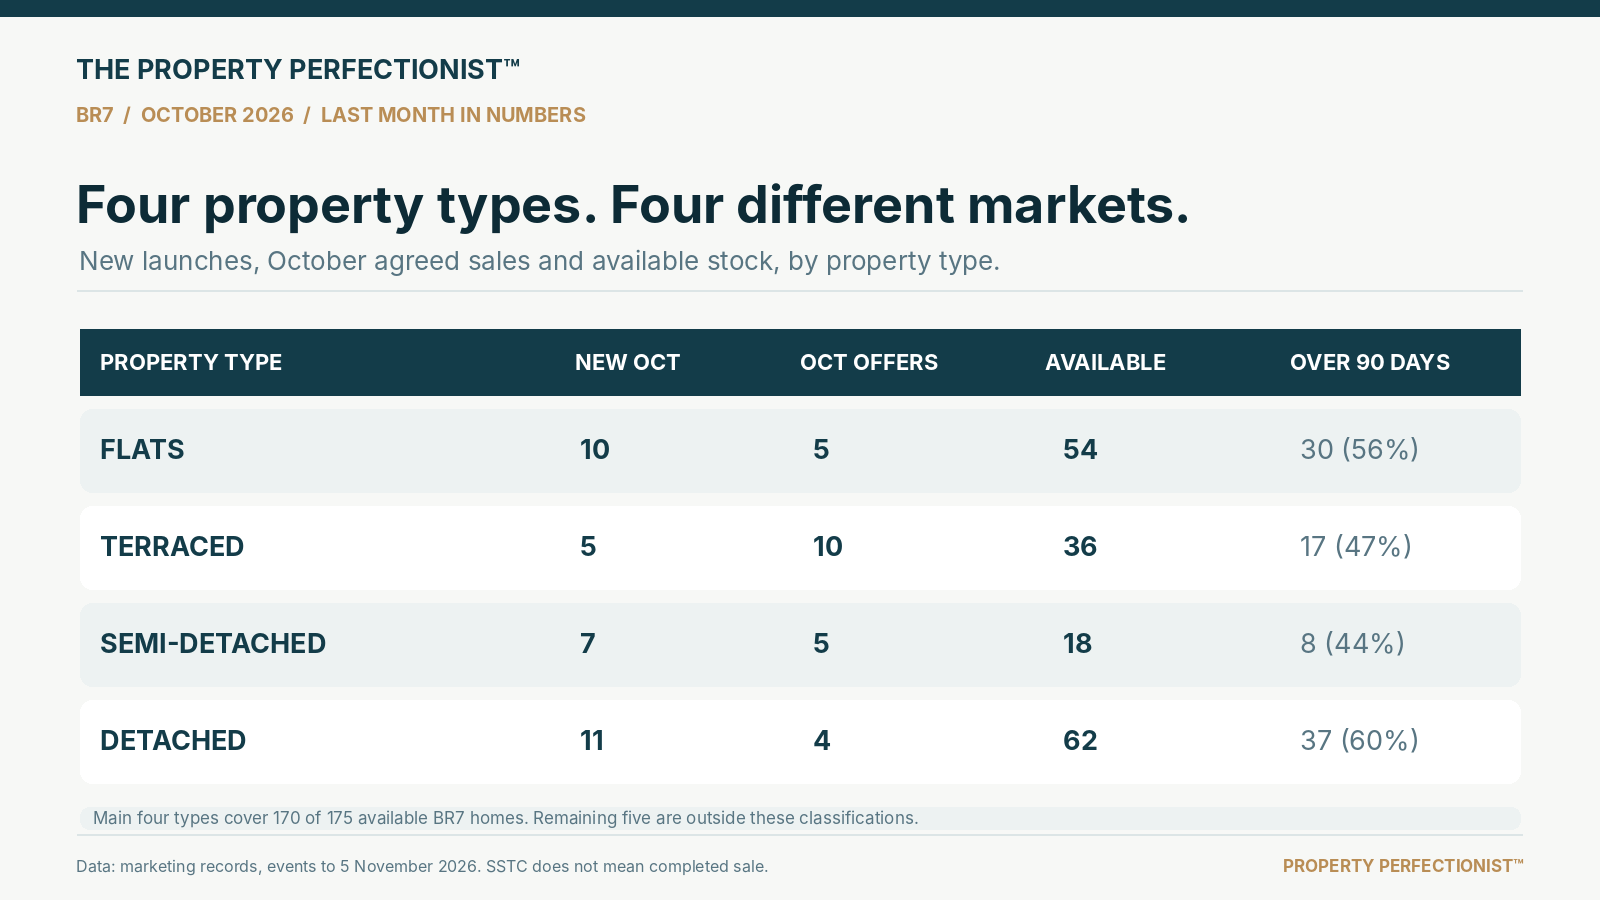
Four main property categories account for 170 of the 175 available listings; five are outside those four classifications.
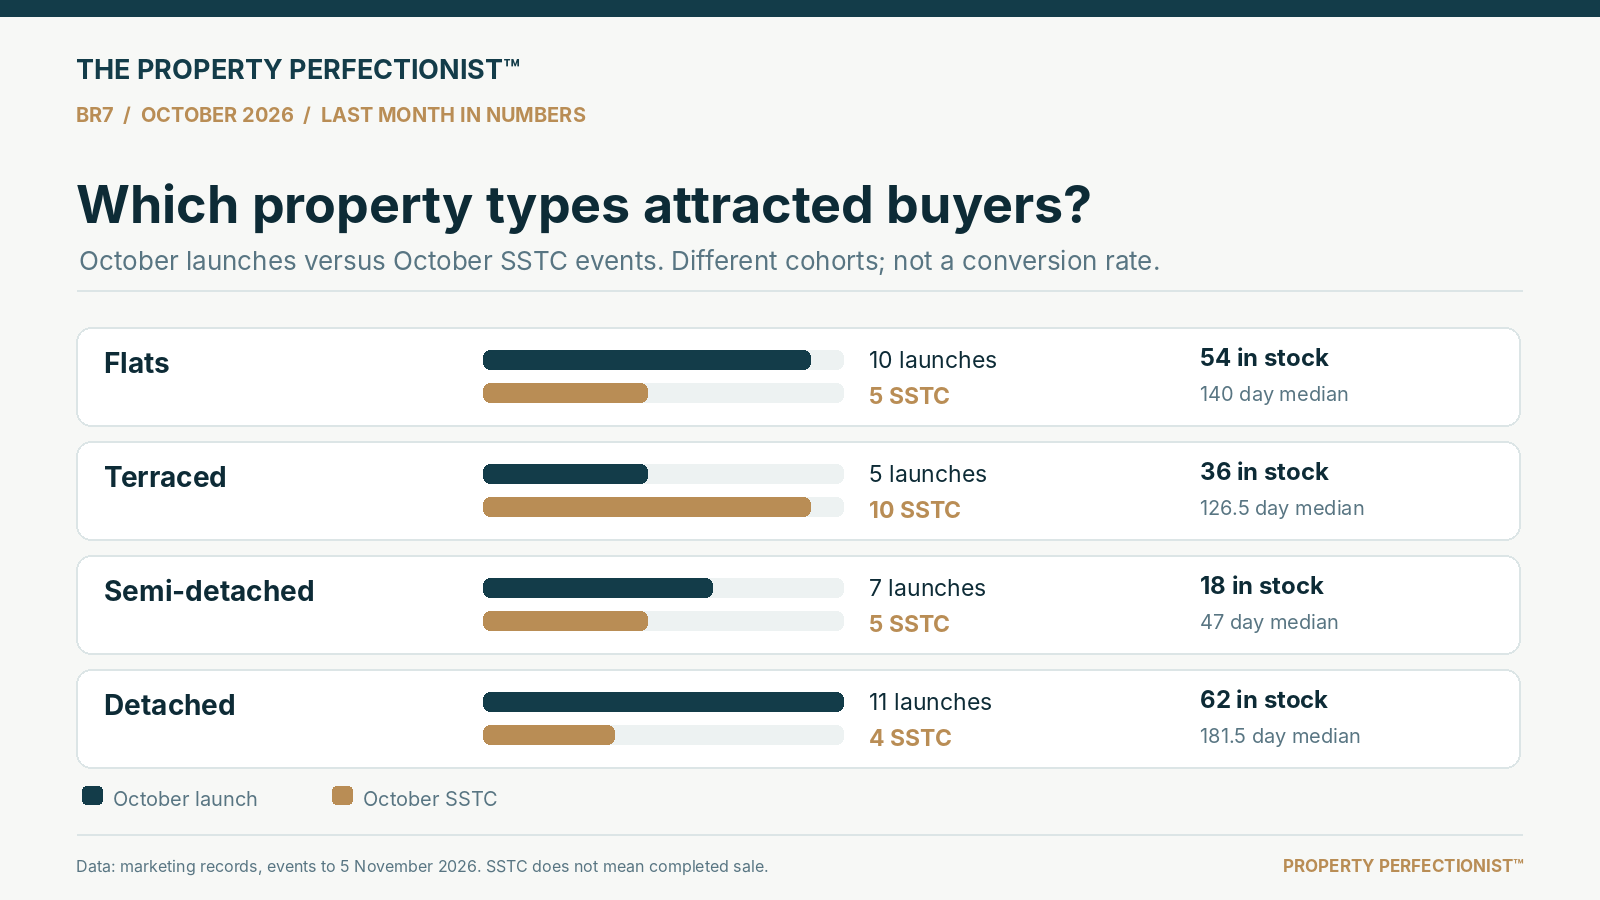
The October launch and October SSTC columns describe different groups; they are not conversion rates.
Terraced houses recorded the most October agreements, with ten. Semi detached homes were the fastest to reach an agreement, with a median of 47 days. At the other end of the spectrum, detached homes recorded just four October agreements against 62 still available at month end.
Flats had their own challenges. Ten were launched in October, but none of those ten reached SSTC by 31 October. Thirty of the 54 flats available at month end had already been advertised for more than 90 days.
The takeaway is not that one property type is universally easier to sell. It is that buyers in each segment face a very different set of alternatives. A well presented family terrace competes with other terraces in its search band; a luxury detached home or retirement flat often needs a very different approach.
Where buyers were most active
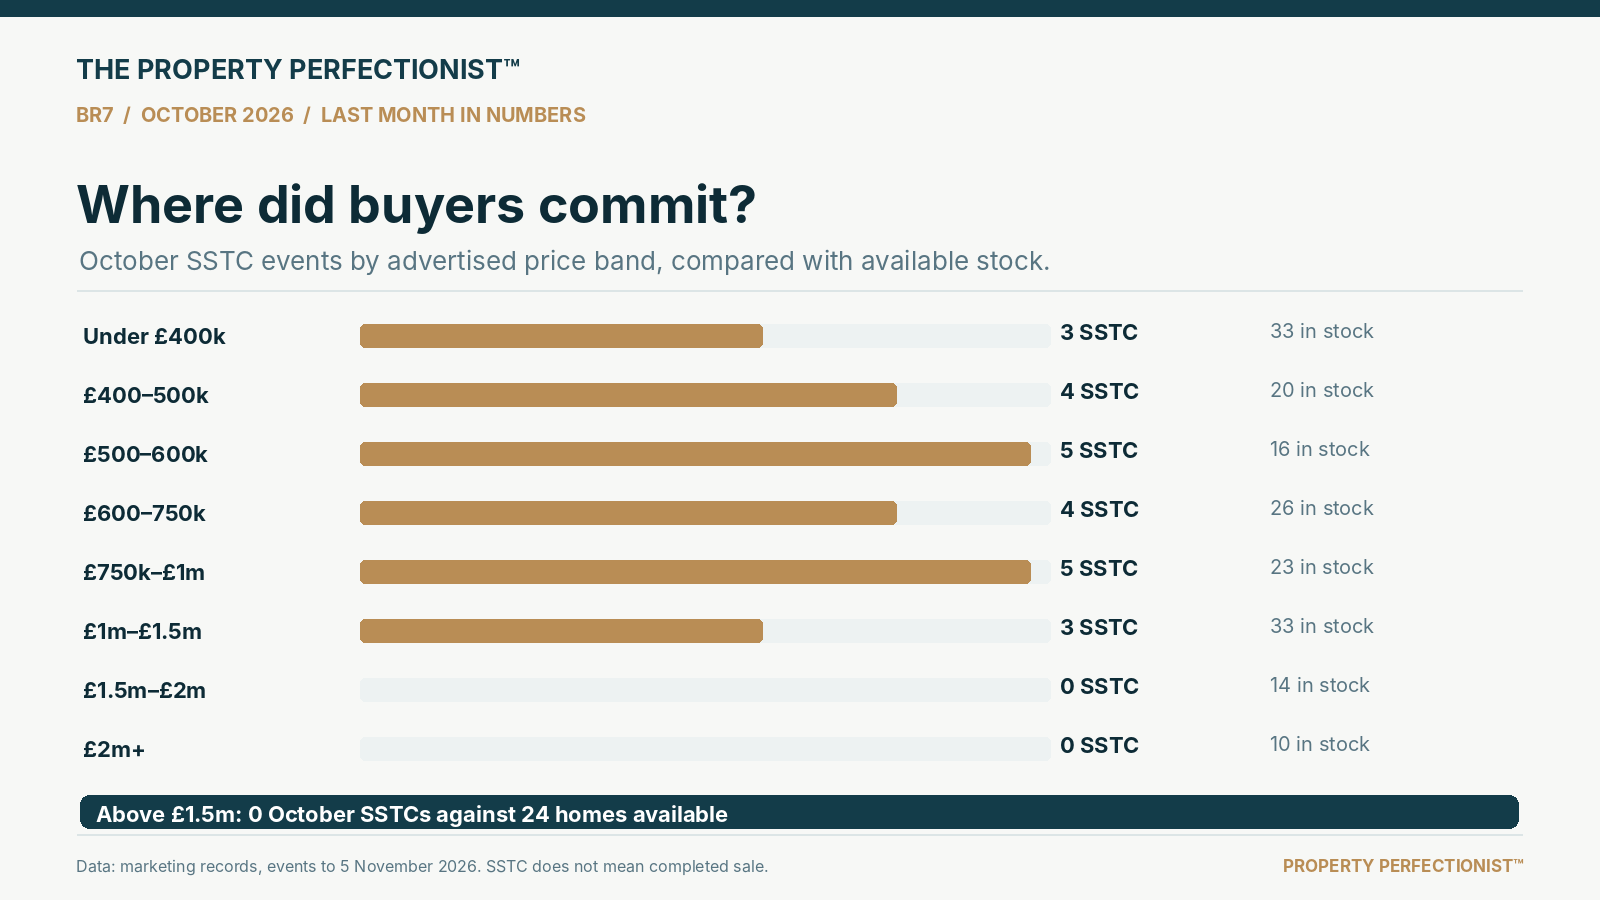
Price bands reflect advertised prices, not completed transaction values.
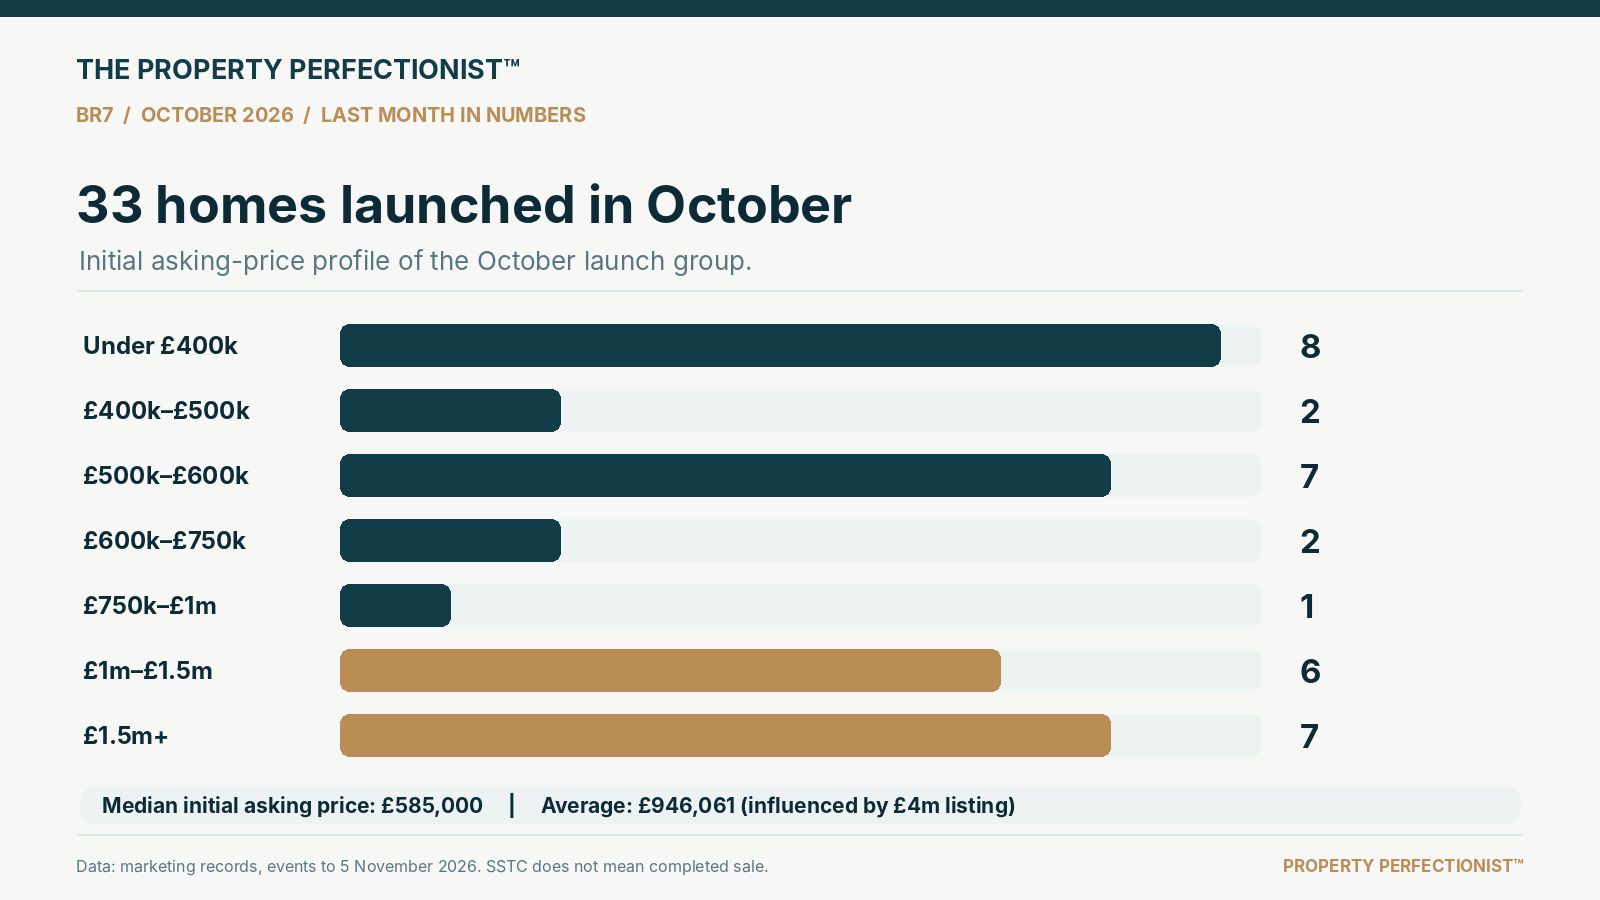
The median October launch asking price was £585,000; the average was influenced by a £4 million listing.
The strongest concentration of October agreements was in the £500,000 to £750,000 asking price bands. Together they produced nine SSTC events. The homes agreeing sales within those bands had median marketing times of roughly 41 to 47 days, noticeably quicker than most other price brackets.
Above £1.5 million, the evidence was rather different: no recorded October SSTC events against 24 available properties at the end of the month. Three homes advertised between £1 million and £1.5 million did go under offer, but their recorded marketing times exceeded 200 days.
This is why postcode wide price averages are only a starting point. The median initial asking price of the 33 October launches was £585,000, but the average was £946,061 because a small number of much more expensive houses pulled it sharply upwards.
The Momentum Window™: why the first few weeks matter
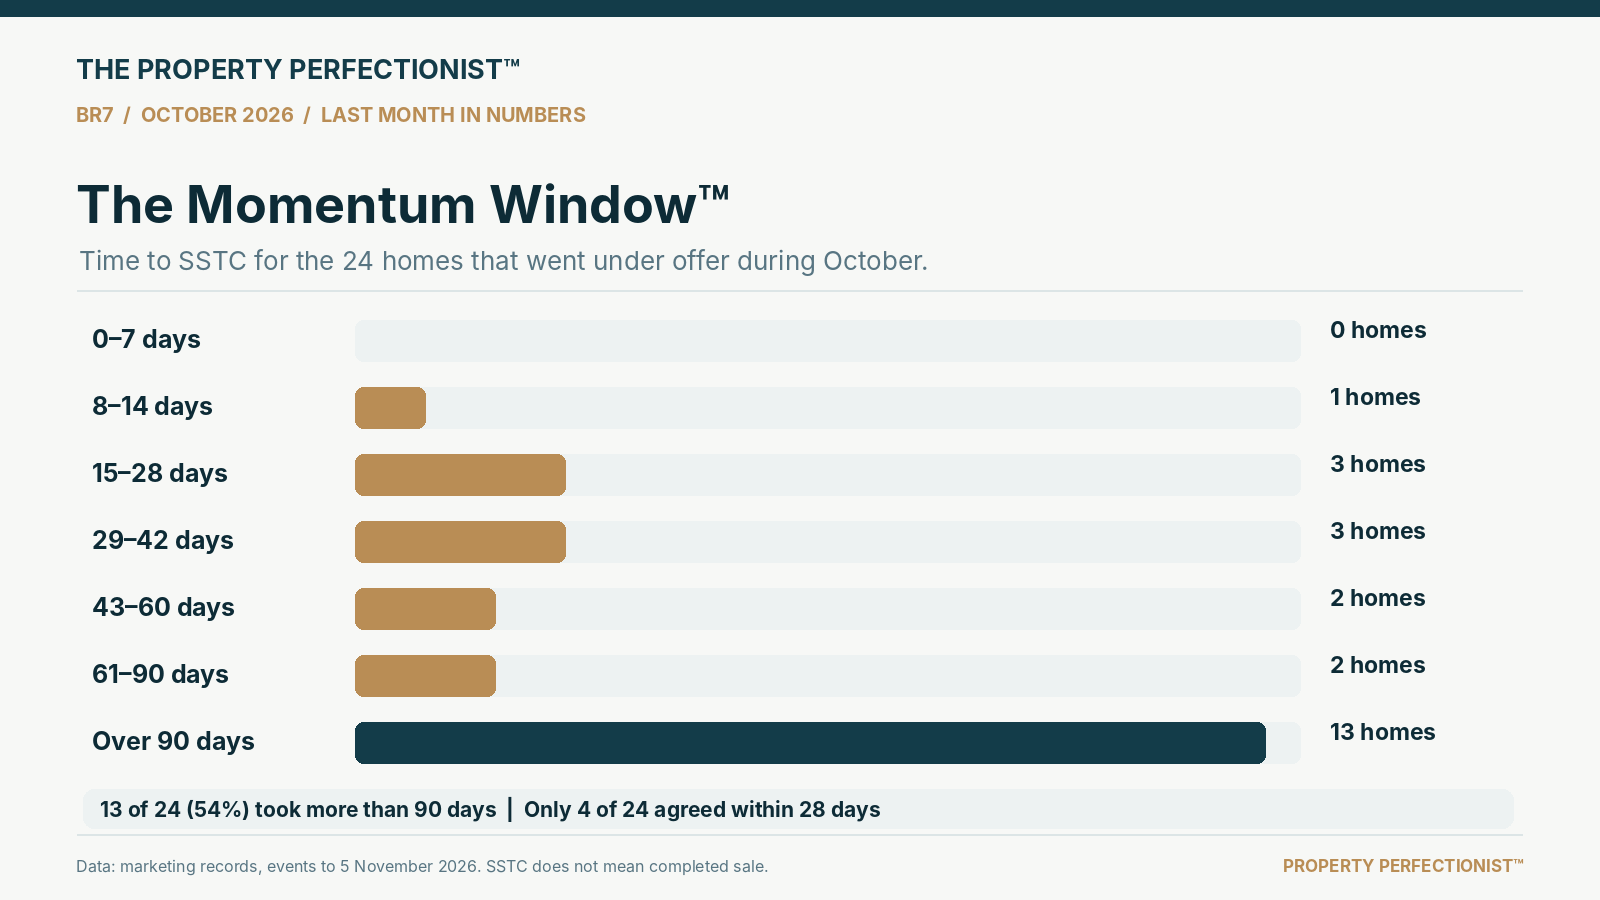
Days to SSTC use the latest recorded launch date, which may reset when a home is relisted.
Of the 24 homes going under offer during October, just four secured their agreements within 28 days of the recorded launch date. Thirteen took more than 90 days, and the overall median marketing time was 127 days.
That does not mean a quick sale was impossible. 5 Belmont Road, Chislehurst, BR7 6HR, a three bedroom terrace advertised at £625,000, went SSTC in just 11 days without a reduction. 50 Mainridge Road, Chislehurst, BR7 6DW, a four bedroom semi advertised at £695,000, agreed an offer after 25 days, also without a recorded reduction.
For a more balanced view of the launch period, I also examined 173 properties launched between April and July, all of which had at least 90 days to find a buyer. Of those, 39 attracted an offer within 28 days, 57 within 60 days and 70 within 90 days. That means 39 of the 70 agreements reached within 90 days came in the first 28 days. Thirty five of those 39 early agreements were on properties without a recorded reduction.
This is the Momentum Window™: the early period when fresh attention can be converted into viewings and offers. It does not prove that all later sales are lost or that marketing alone explains the difference. It does show why I put so much emphasis on positioning before a property goes live.
Why a reduction is not a strategy on its own
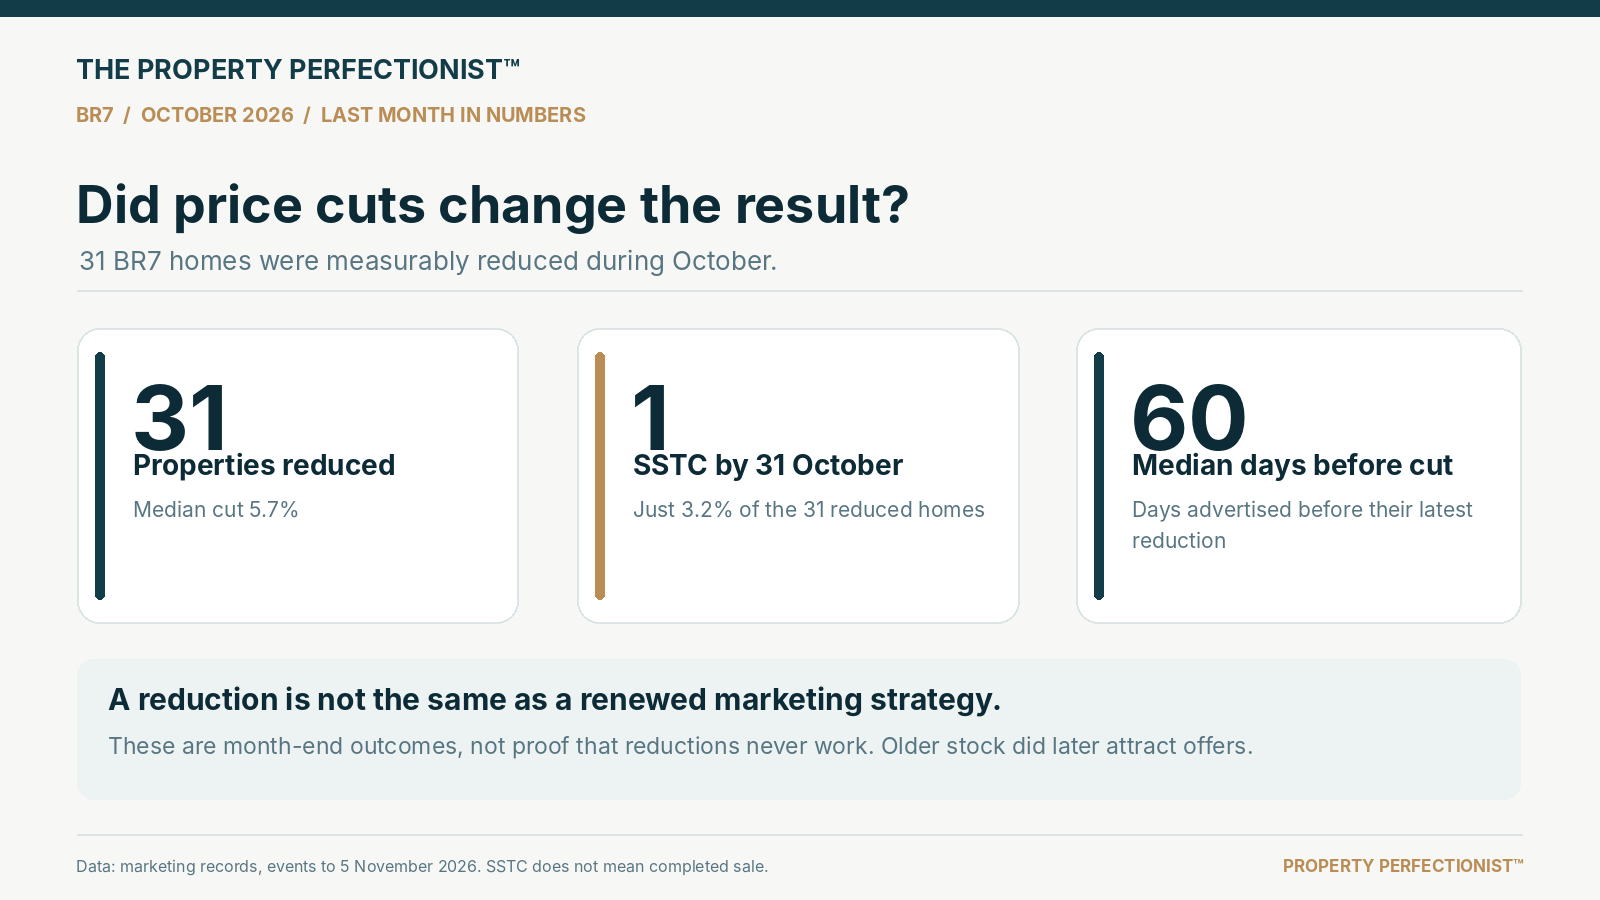
Asking price cuts are not achieved sale price discounts, and a later offer may still follow.
31 BR7 homes recorded measurable asking price reductions during October. The median recorded reduction was 5.7%, and the median time on the market before the latest reduction was 60 days. Just one of those 31 homes had become SSTC by 31 October.
That is a short term observation, not evidence that reductions never work. In fact, 12 of the 24 October agreements involved properties with recorded reductions at some stage. The difference is that reductions were disproportionately associated with homes that had already been marketed for a long time.
Two addresses illustrate the point. 80 Walden Road, Chislehurst, BR7 5DL, had moved from an original £1.2 million asking price to £950,000 and remained available. 26 Sunnyfield Road, Chislehurst, BR7 6QP, had moved from £850,000 to £650,000 and was still being marketed after a relaunch. Neither asking price change guarantees an offer because buyers also consider condition, presentation and alternative homes.
The question I would ask before reducing is whether we have properly identified the reason buyers are not engaging. Would the change place the property in a different search band, or would it simply become the same advert at a lower price?
The problem with older stock
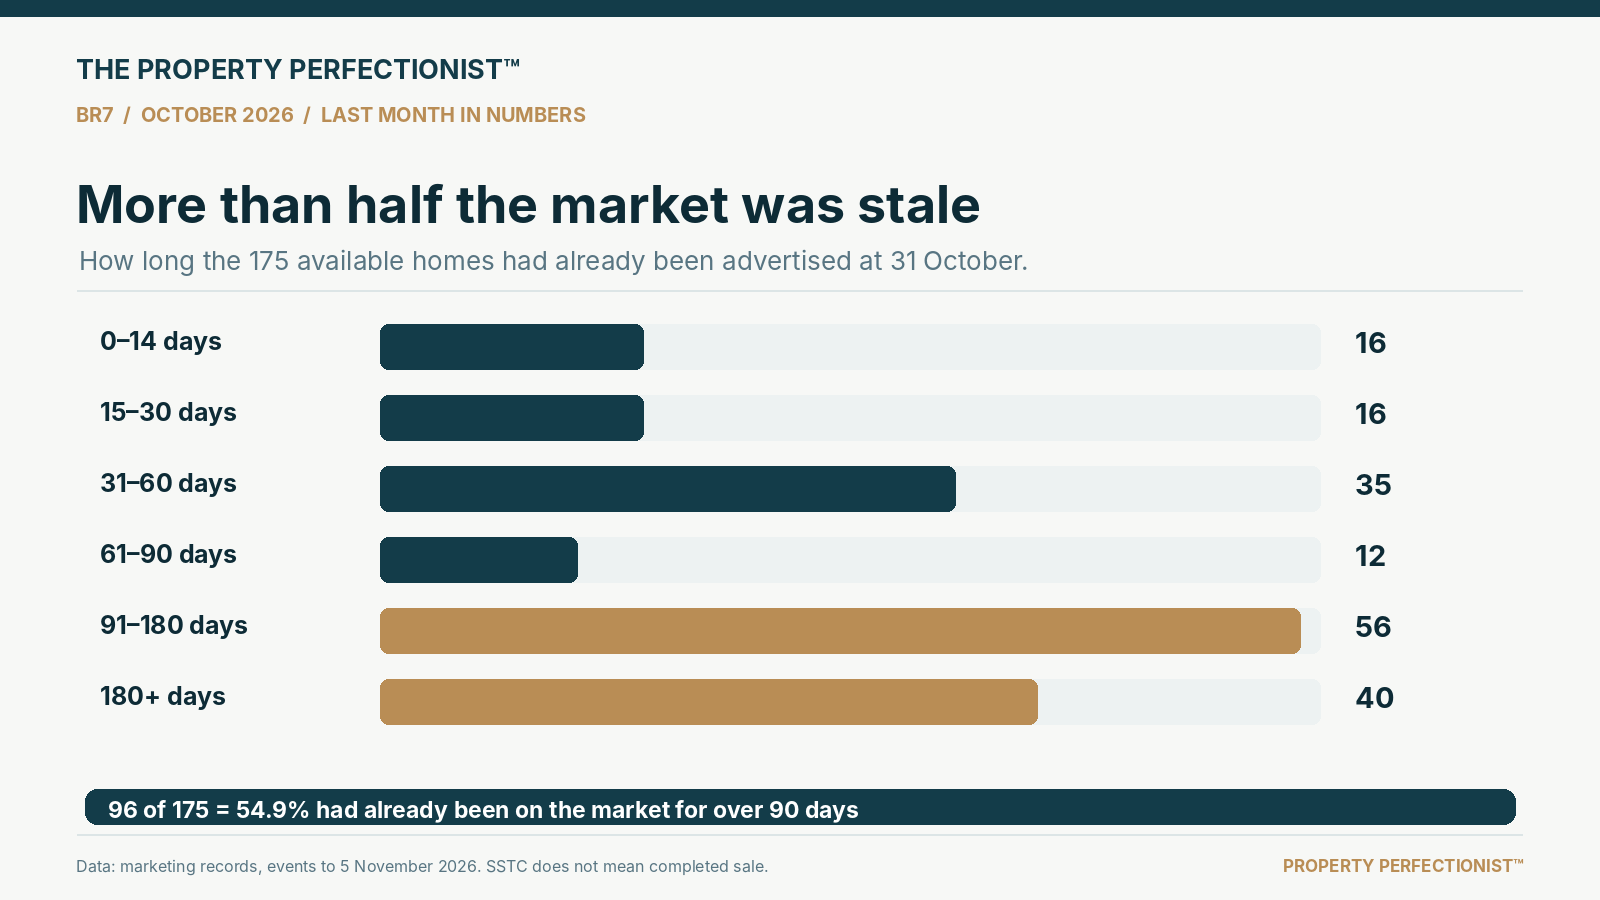
96 of 175 homes had been available for more than 90 days at the end of October.
At 31 October, 175 properties were still available in BR7. Of those, 96 had been on the market for more than 90 days, representing 54.9% of the available stock. Forty had been advertised for more than 180 days.
The most heavily affected categories were detached houses, where 37 of 62 available properties had exceeded 90 days, and flats, where 30 of 54 had reached that point.
Prolonged exposure does not automatically mean there is something wrong with a property. But it changes how buyers interpret an advert. They begin asking why it is still available and comparing it with newer alternatives. The longer a listing is live, the more important it becomes to give the market a convincing reason to look again.
BR7 5 and BR7 6 are not interchangeable
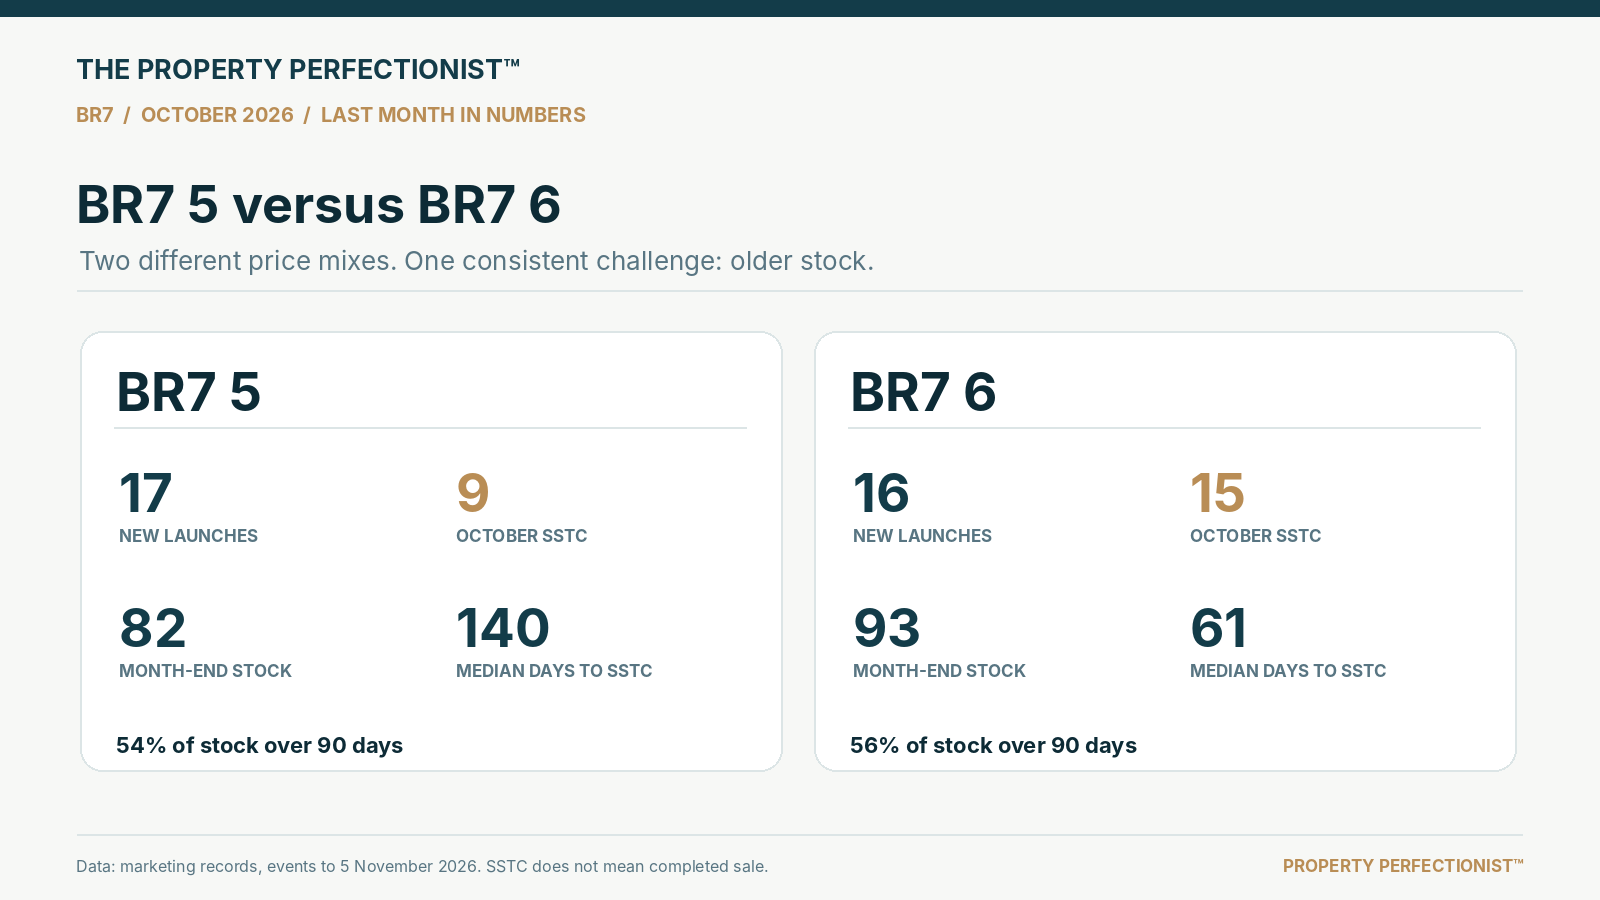
The sectors differ by property mix and price, so the results should not be treated as a simple league table.
BR7 6 recorded 15 October SSTC events, compared with nine in BR7 5. Homes reaching SSTC in BR7 6 had a recorded median marketing time of 61 days, compared with 140 days in BR7 5.
But there is an important qualification. BR7 5 contains a larger concentration of homes above £1 million, while BR7 6 has more mainstream semi detached and terraced stock. Their shares of available homes older than 90 days were very similar: 54% in BR7 5 and 56% in BR7 6.
It is a reminder that good market analysis needs to move beyond the postcode district and into the specific search market of the property. Even within Chislehurst, buyers make choices between very different streets, buildings and house types.
What happened above £1.5 million?
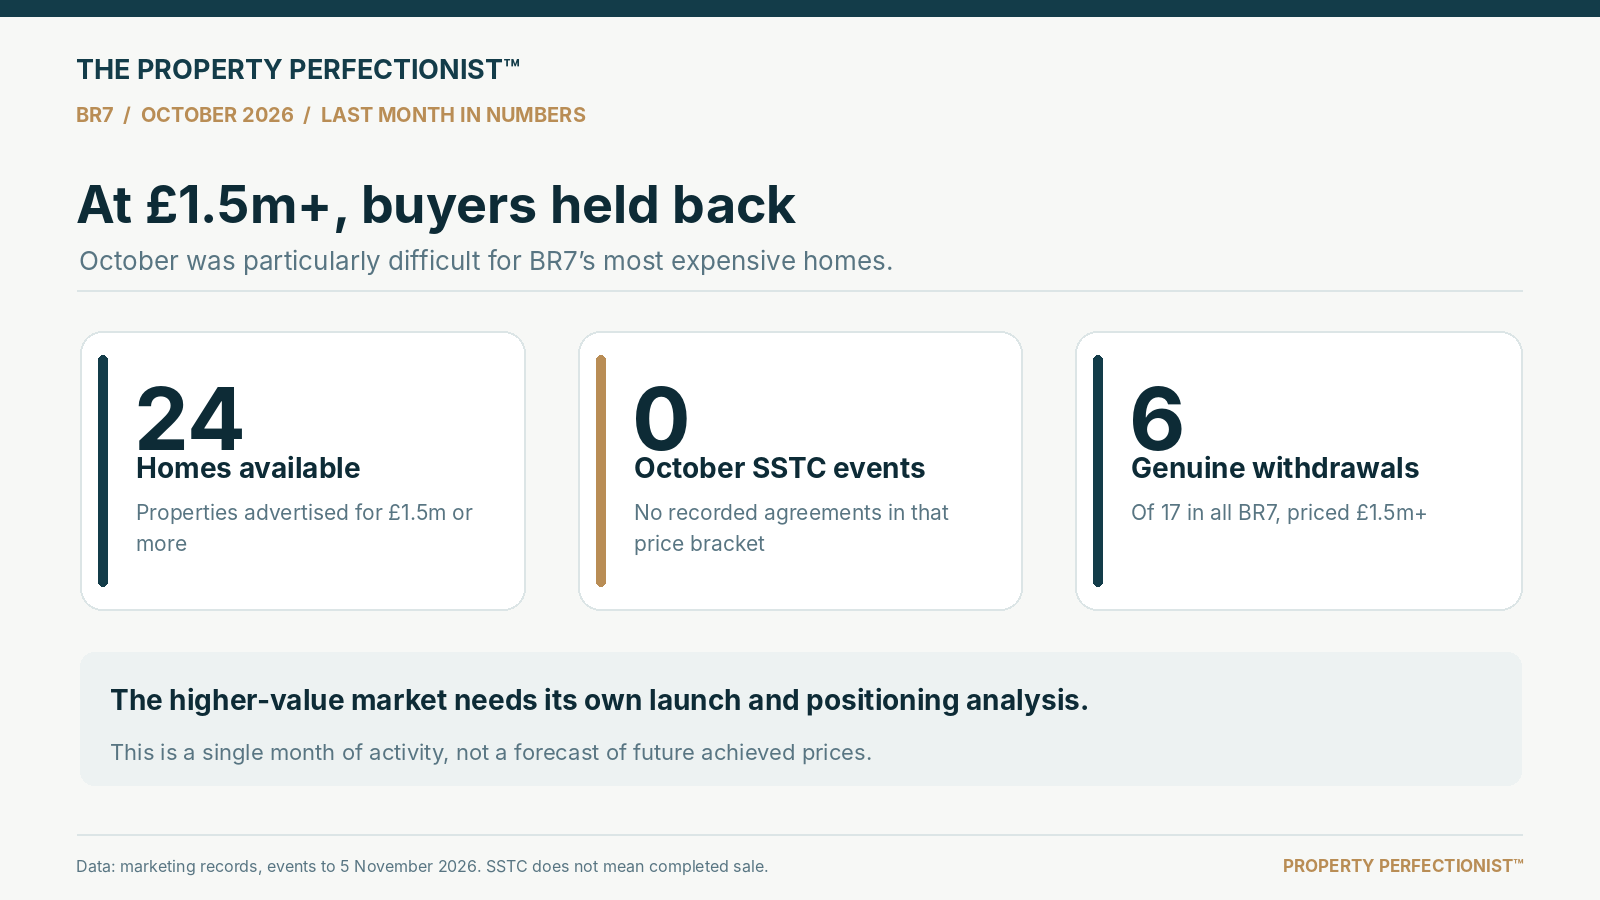
One month cannot establish future sale prices, but it does reveal the competitive pressure facing higher value vendors.
The luxury segment had a particularly quiet October. There were 24 available listings asking £1.5 million or more and no October SSTC events in that band. Six of BR7’s 17 genuine October withdrawals were at £1.5 million or above.
That does not mean buyers no longer want substantial homes in Chislehurst. It means that sellers at the higher end need especially careful positioning. Larger houses are not interchangeable, and buyers consider the complete proposition: accommodation, condition, layout, location and the scale of any work they would need to undertake.
Four individual homes reveal the bigger story
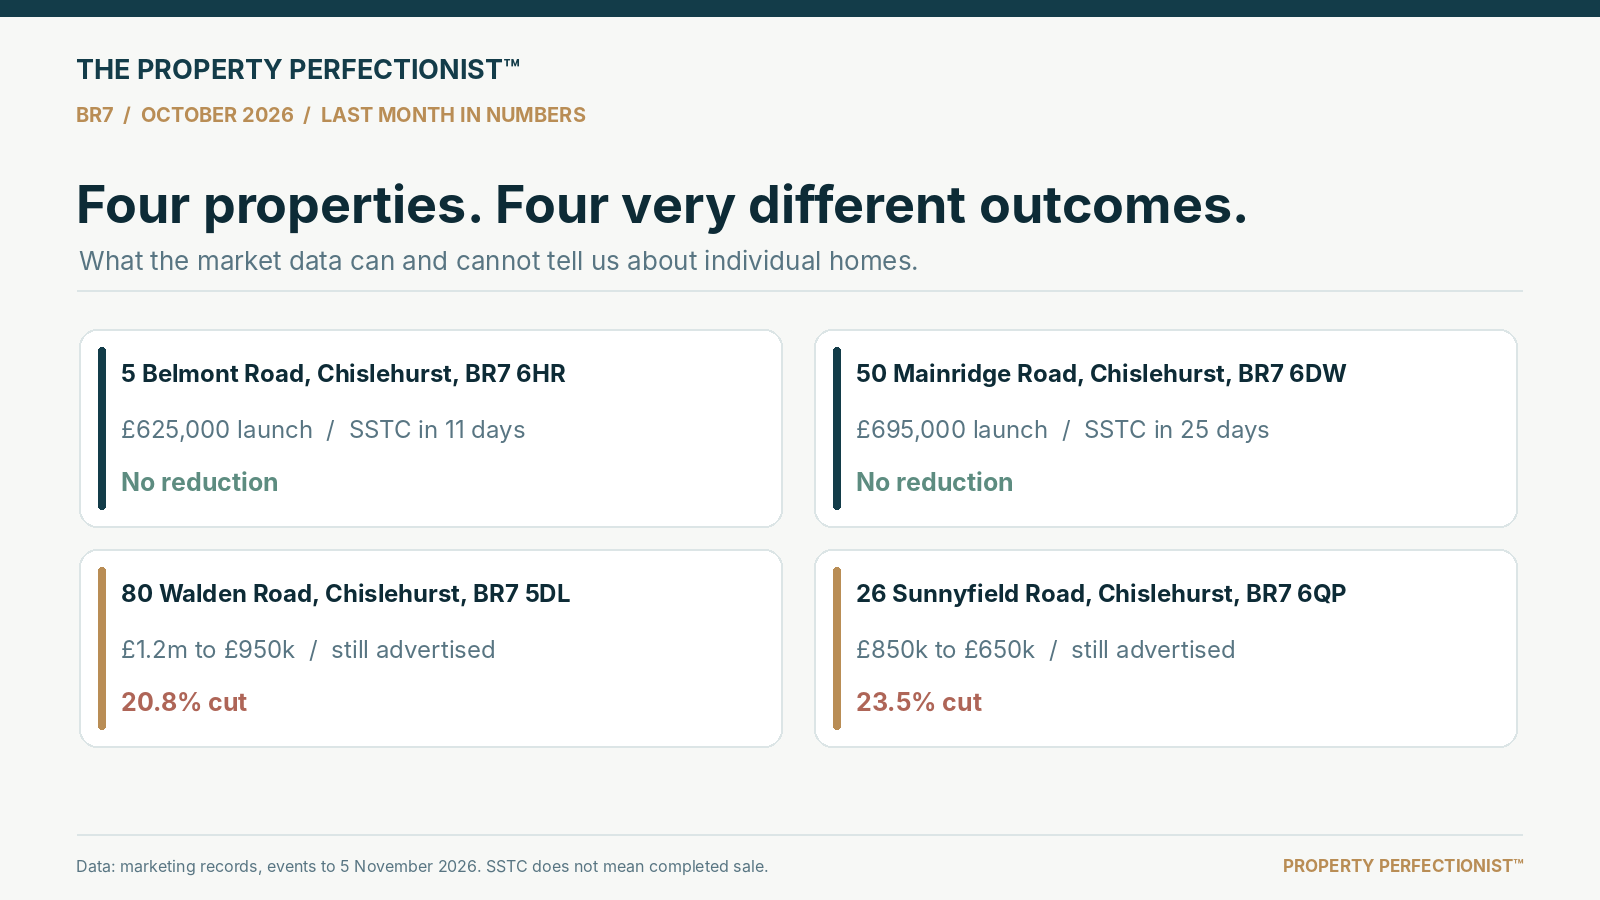
Fast agreements on some unreduced homes contrasted with substantial cuts on others still available.
Market averages are useful, but individual examples often make the buyer psychology easier to understand. These are advertised prices and marketing outcomes, not verified completed sale prices.
2 Benson Mews, Chislehurst, BR7 6FD, was advertised at £575,000 on 14 September and went under offer 25 days later, with no recorded reduction. By contrast, 4 Marlings Close, Chislehurst, BR7 6RL, was first advertised at £1,575,000 in March, reduced to £1,225,000 and eventually went under offer in October after 207 recorded days.
25 Highfield Road, Chislehurst, BR7 6QY, is also worth mentioning. It became SSTC on 14 October but returned to the market after a fall through on 27 October. It is one more reason not to confuse an agreed offer with a completed sale.
What does agent activity tell us?
It is possible to compare recorded October activity across agents, which I have anonymised as Agent 1 to Agent 6, provided we do not pretend that a firm marketing mainly luxury detached properties faces the same conditions as one handling more mid priced terraces and semis.
| Agent | Launched | Sales agreed | For sale at month end | For sale over 90 days |
|---|---|---|---|---|
| Agent 1 | 7 | 9 | 28 | 12 |
| Agent 2 | 5 | 6 | 41 | 19 |
| Agent 3 | 5 | 2 | 29 | 17 |
| Agent 4 | 2 | 2 | 17 | 14 |
| Agent 5 | 2 | 1 | 6 | N/A |
| Agent 6 | 1 | 1 | 5 | N/A |
October figures. N/A means the figure was not supplied.
These figures are a snapshot of recorded listings, not a ranking of agent quality or an agent level conversion analysis. October agreements include homes launched in earlier months. The sample sizes and price mix vary considerably, and the listed agents do not account for every BR7 property.
My Property Perfectionist™ verdict
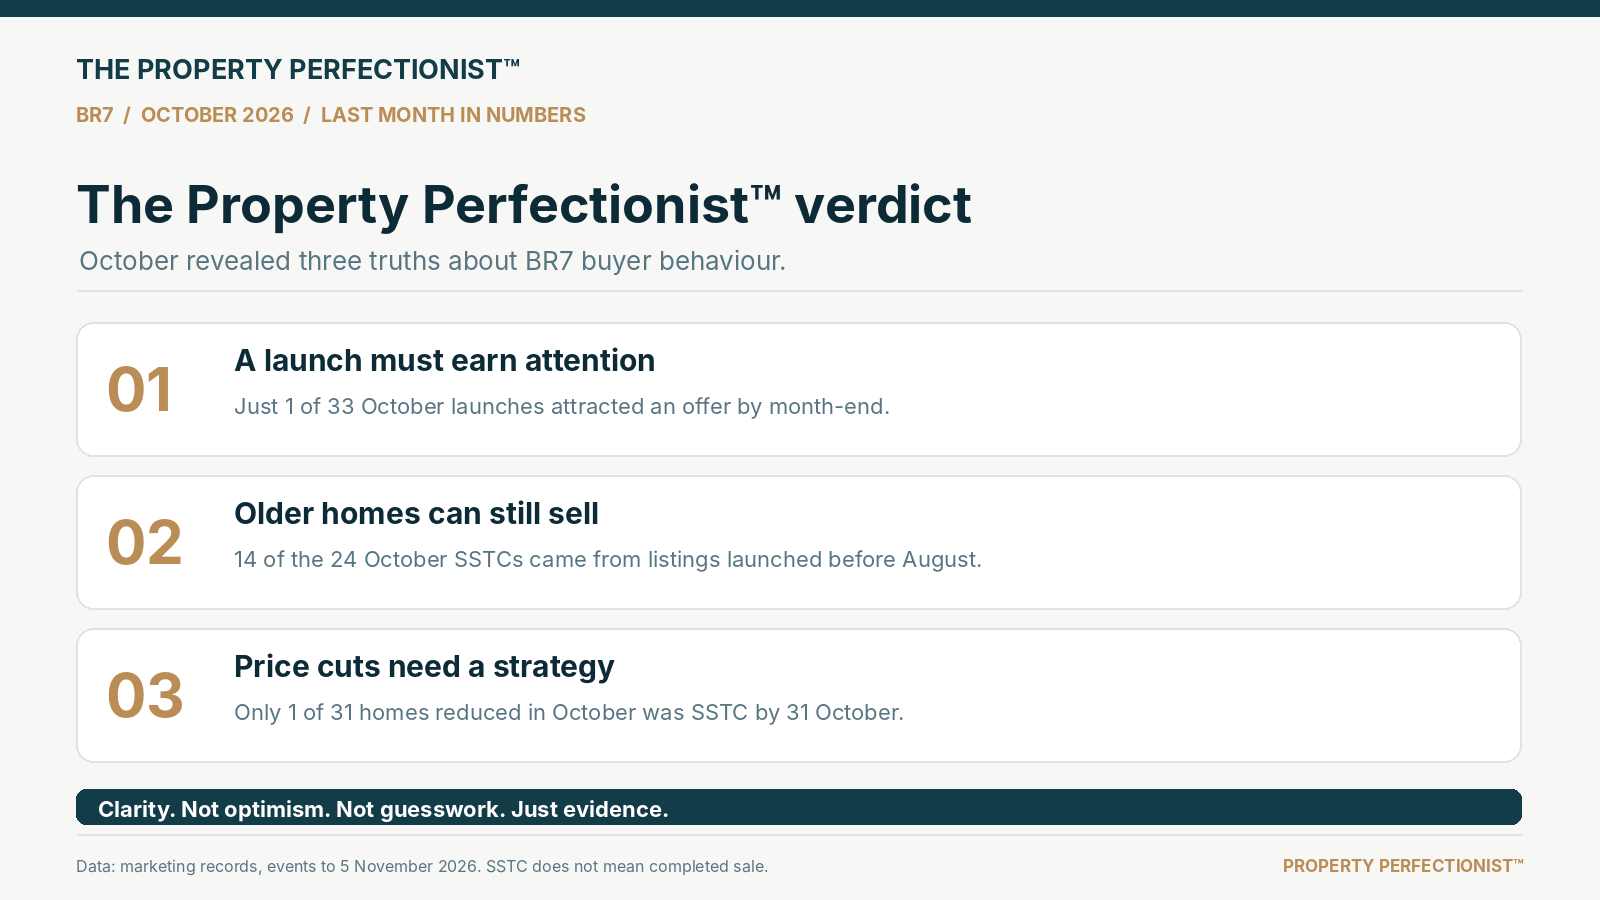
Every unsold property leaves clues.
October does not show a market in which buyers had simply disappeared. It shows a selective market in which the most active demand was concentrated in particular types and price bands, while a large amount of older stock continued to compete for attention.
Some family houses attracted offers quickly at their original asking prices. Others needed months of exposure and subsequent reductions. Above £1.5 million, October produced no recorded SSTC events. The meaningful question is not whether your property is “good” or “bad”. It is which alternatives buyers are choosing instead, and what would make yours stand out.
Already on the market? Ask your agent which directly competing homes have secured offers, how their marketing and presentation differ from yours, and what specifically will change to encourage buyers to reconsider.
THE PROPERTY PERFECTIONIST™
Want to know what the evidence says about your property?
I prepare individual Market Intelligence Reports to examine buyer activity, competing listings and the clues behind a property’s market performance.
Request your free Market Intelligence Report
James Hall · over 18 years in property · james.hall@expuk.com · 07855 828 736
Clarity. Not optimism. Not guesswork. Just evidence.
Related local reports: my BR2 October market report.
How the figures were measured
This report examines BR7 5 and BR7 6 marketing records for 1 to 31 October 2026. The underlying dataset is a 7 November snapshot, with events counted only when dated on or before the 5 November verification cut off. Month end stock was reconstructed from the latest available event dates.
All property prices quoted are advertised asking prices, not achieved sale prices. An SSTC event means an offer was agreed subject to contract; it does not establish completion. Relaunched properties may have reset listing dates, and the source holds only the latest recorded reduction date, so complete individual marketing histories cannot always be rebuilt. Genuine withdrawals have been distinguished from portal removal events where a property was already sold or under offer. Percentages have been rounded, and small postcode, type and agent groups should be interpreted carefully.
The four principal property types cover 170 of the 175 properties available at month end. Five listings do not sit within those four categories; the total stock figure includes them. The 96 available for over 90 days applies to the full 175 property inventory.
What does this mean for your home?
Not ready for a visit? I can prepare a free Market Intelligence Report to show you the sales evidence and the homes buyers will compare with yours. There is no obligation.


Leave a Reply