The Property Perfectionist™ | October 2026 | Data snapshot 4 November 2026
October was not one property market in BR3. It was several very different markets operating side by side. Some terraced houses attracted offers within a week, while parts of the flat market carried substantial stock that had already been advertised for months. Here is what the recorded activity tells us about Beckenham, Park Langley and the wider BR3 district.
What happened in October?
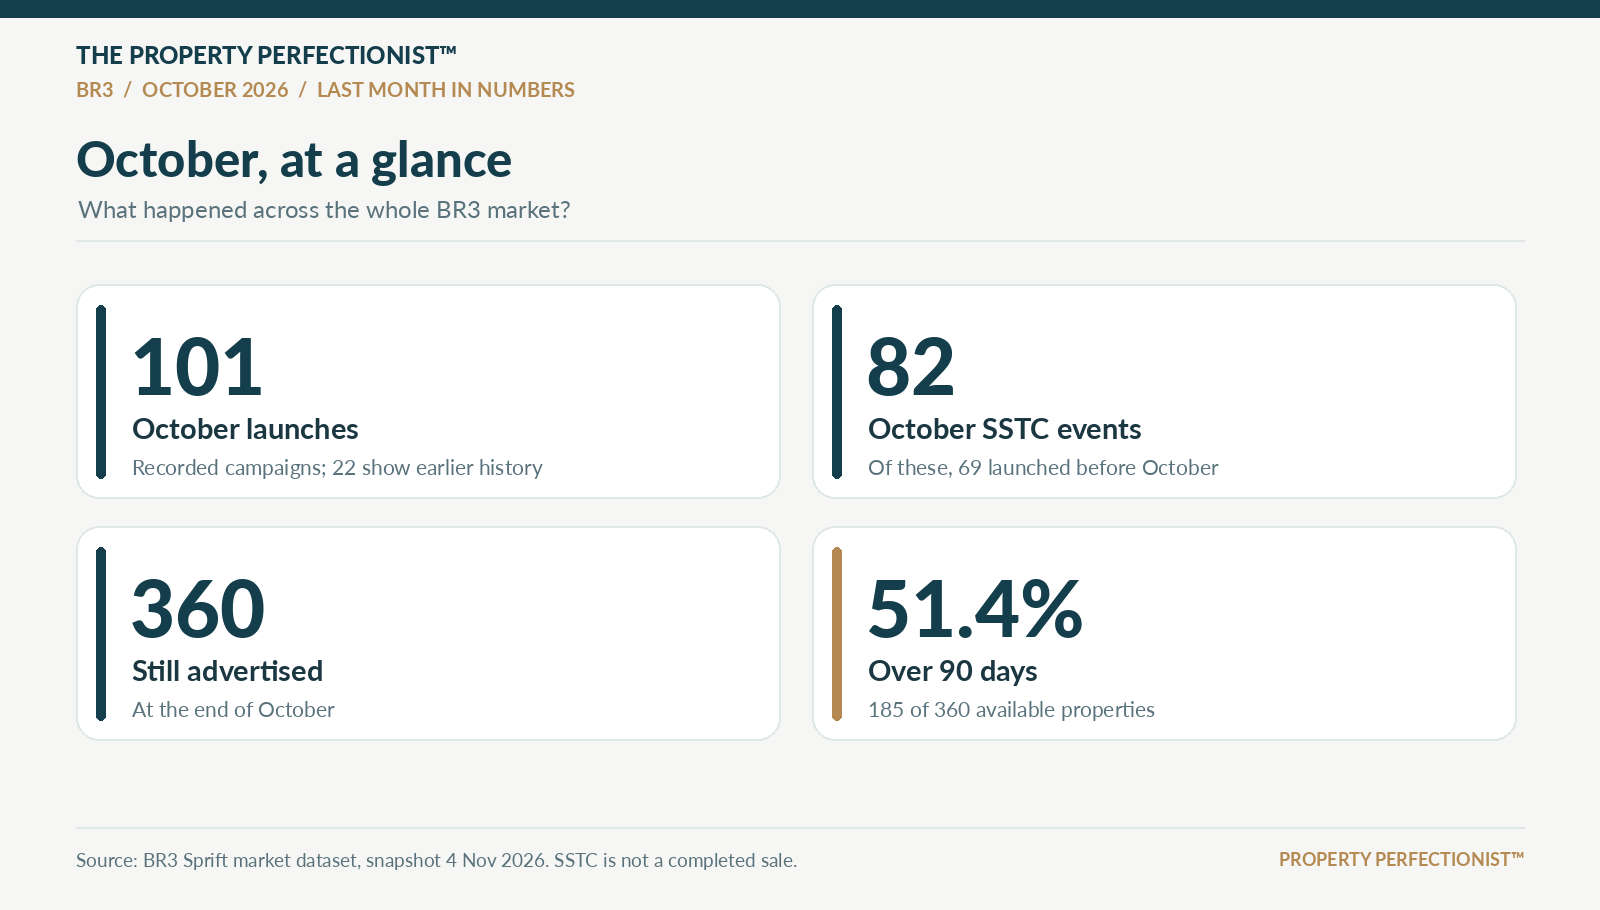
October recorded 101 new marketing campaigns and 82 dated under-offer events. Those are different groups: 69 of the 82 homes going under offer had been listed before October. Of the 101 October launches, 13 have confirmed October offer dates, with a further six marked under offer but missing a usable date. At the month-end snapshot, 360 homes were still available; 185, or 51.4%, had already been advertised for more than 90 days. We also found 22 October campaigns with evidence of earlier marketing activity, so “new listing” does not always mean a genuinely new instruction.
Flats, terraces, semis and detached: which performed better?
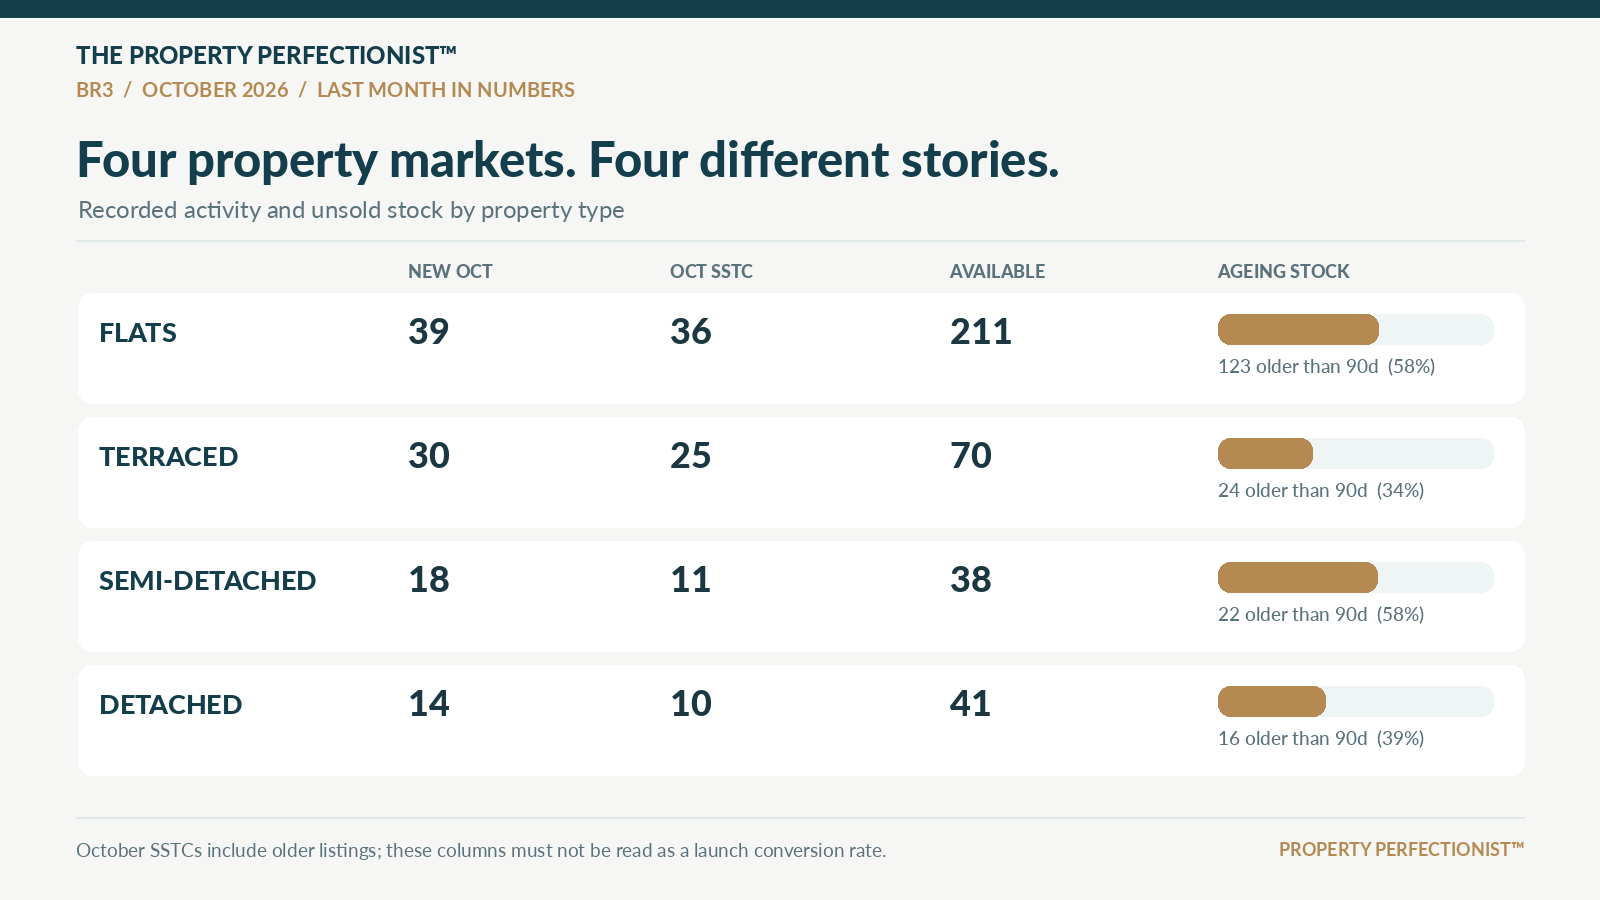
The relative performances are revealing. Terraced houses had 25 October offer events against 70 homes still available; flats had 36 October offers against a much larger available stock of 211. More tellingly, only 34% of available terraces were older than 90 days, compared with 58% of flats and semi-detached houses. These are not sales conversion rates, but they show where unsold stock is becoming entrenched. Mature launch-cohort results give us a fairer comparison later in this report.
Flats and terraced houses: the price bands that matter
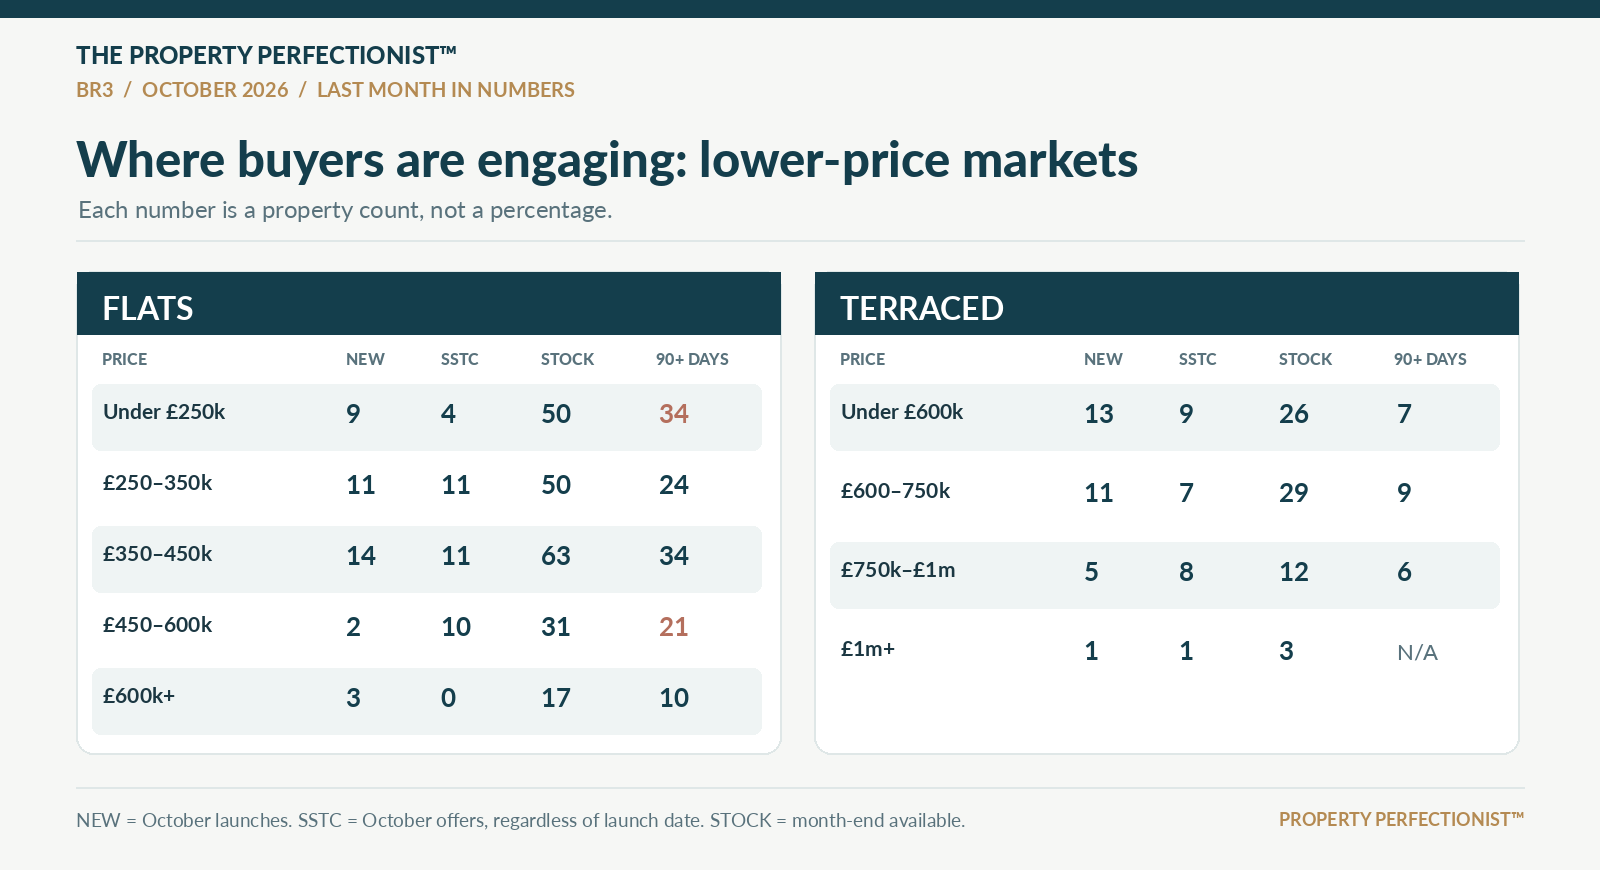
The flat market deserves its own investigation. At under £250,000, there were only four October SSTC events against 50 available flats, of which 34 had already been listed for more than 90 days. This band contains a significant amount of retirement and sheltered accommodation, so its difficulties should not be generalised to every first-time buyer flat. The £250,000 to £350,000 market was more active, recording 11 October offers, although 24 of its 50 available flats were still older than 90 days. At £450,000 to £600,000, 21 of 31 available flats were already over 90 days old. That suggests more substantial competition for vendors of higher-priced flats.
Terraced houses show the clearest buyer engagement. Below £600,000, nine properties went under offer during October, and the successful listings in this band had a median marketing duration of 11 days. Consider 20 Aylesford Avenue, BR3 3SD, which went under offer in seven days at an advertised £575,000, and 20 Eden Road, BR3 4AT, which took nine days at £400,000. At the higher end, 167 Ravenscroft Road, BR3 4TN, found a buyer in eight days at an advertised £875,000. These figures are asking prices when the properties went under offer, not completed sale prices. The lesson is not simply “cheaper sells”; it is that properties at several price points can generate rapid engagement when buyers see a compelling proposition.
Semi-detached and detached homes: a more selective market
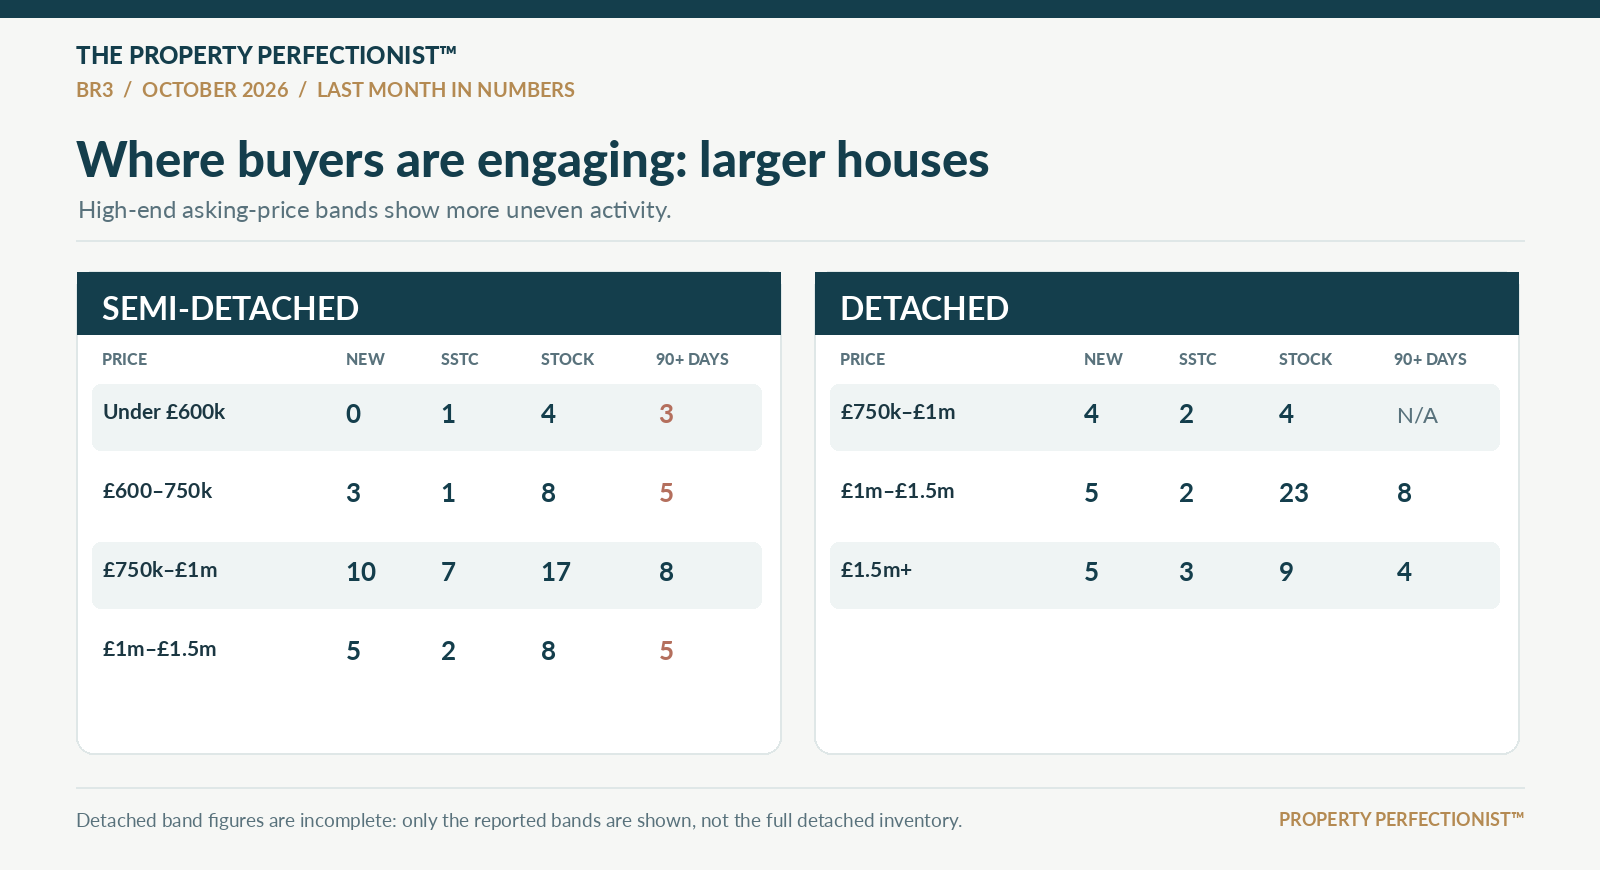
Semi-detached homes were more selective. The £750,000 to £1 million band accounted for seven October under-offer events, while 17 homes remained available. The contrast between individual cases is stark: 9 Woodmere Way, BR3 6SJ, went under offer in seven days at an advertised £935,000, while 47 Village Way, BR3 3NA, took 143 days and moved from an original £950,000 asking price to £750,000 before going under offer. This illustrates very different marketing journeys, but we would need condition, layout and presentation evidence before assigning the difference to price alone.
Detached houses produced two very different stories. 3 Wickham Way, BR3 3AA, a six-bedroom home advertised at £2 million, went under offer in four days. Meanwhile, 23 Uplands, BR3 3NB, remained available after its asking price moved from £1.25 million to £1 million. The £1 million to £1.5 million detached band carried 23 available properties against just two October under-offer events. There is buyer demand at premium levels, but a headline asking price does not tell us whether a home will generate strong interest.
The £7.85 million asking-price reduction story
Across BR3, 181 of the 360 available properties showed recorded asking-price reductions. Together, those cumulative advertised reductions amounted to approximately £7.85 million. The median cut among reduced available homes was £25,000, or 6.7%. That is not money lost from completed transactions; it is the combined difference between initial and current asking prices. Eighty-five available or tracked listings had their latest recorded reduction dated October. The research keeps only the latest reduction date, so we cannot reconstruct every cut or identify the first reduction for every property.
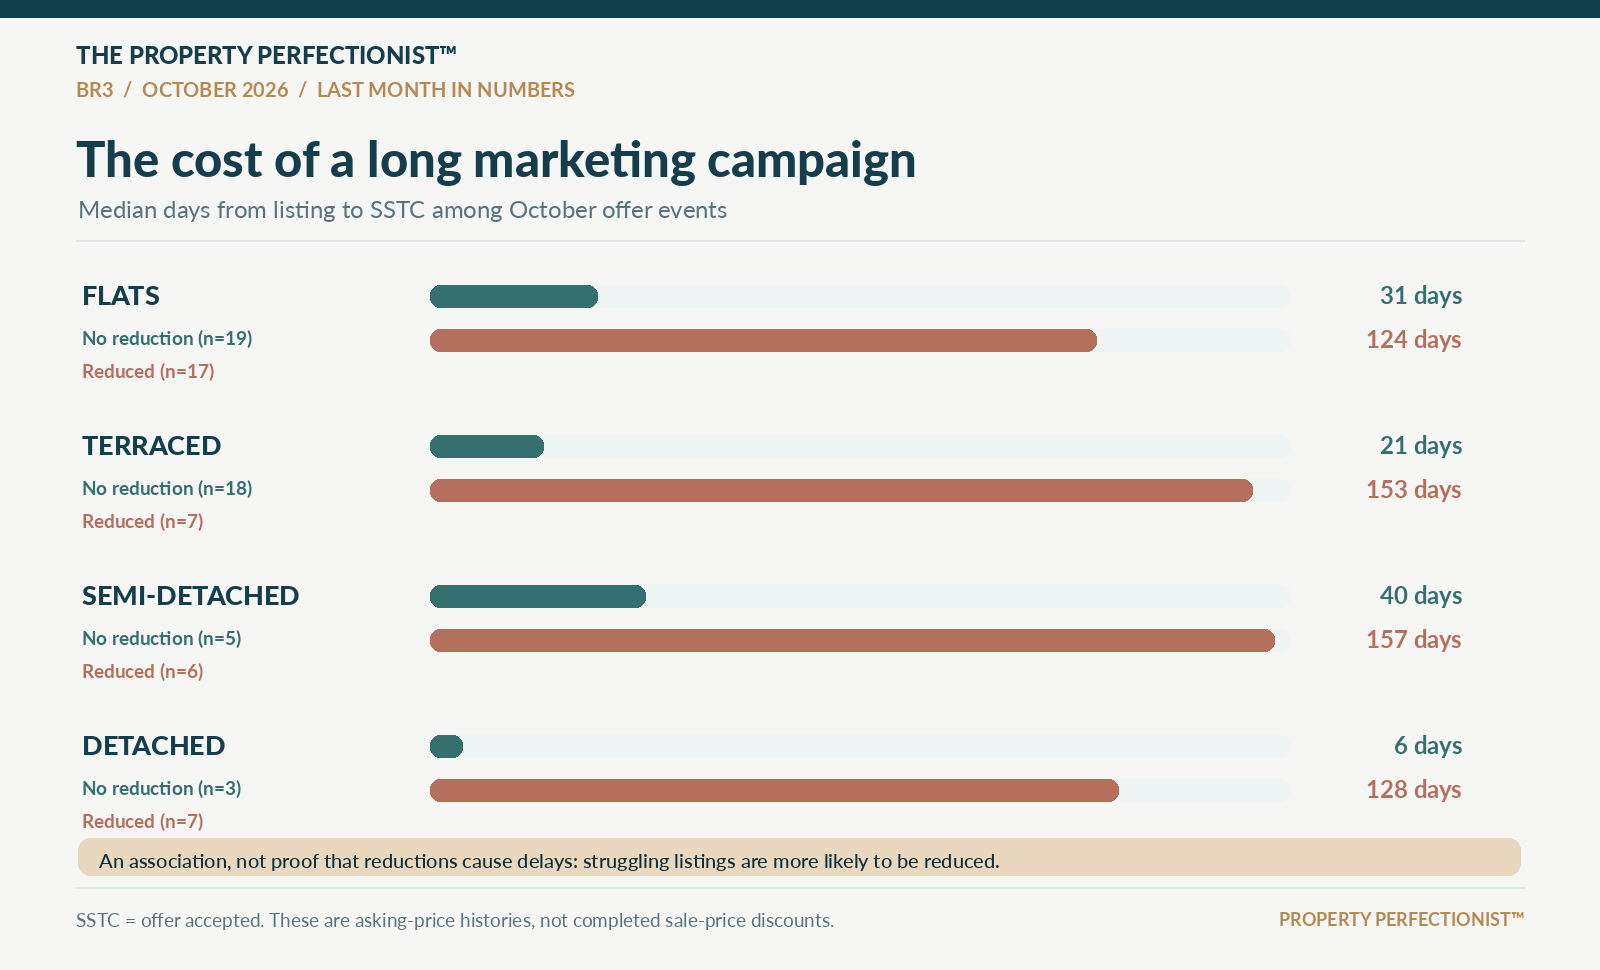
The gap between reduced and unreduced properties is substantial. Among terraced houses that went under offer in October, unreduced listings had a median marketing time of 21 days, compared with 153 days for those with a recorded reduction. Flats showed 31 versus 124 days; semi-detached properties 40 versus 157; detached properties six versus 128. This is an association, not causation. Often the property was reduced precisely because it had already been sitting on the market. What it does tell us is how hard a weak launch can be to recover from.
The Momentum Window™: first 30, 60 and 90 days
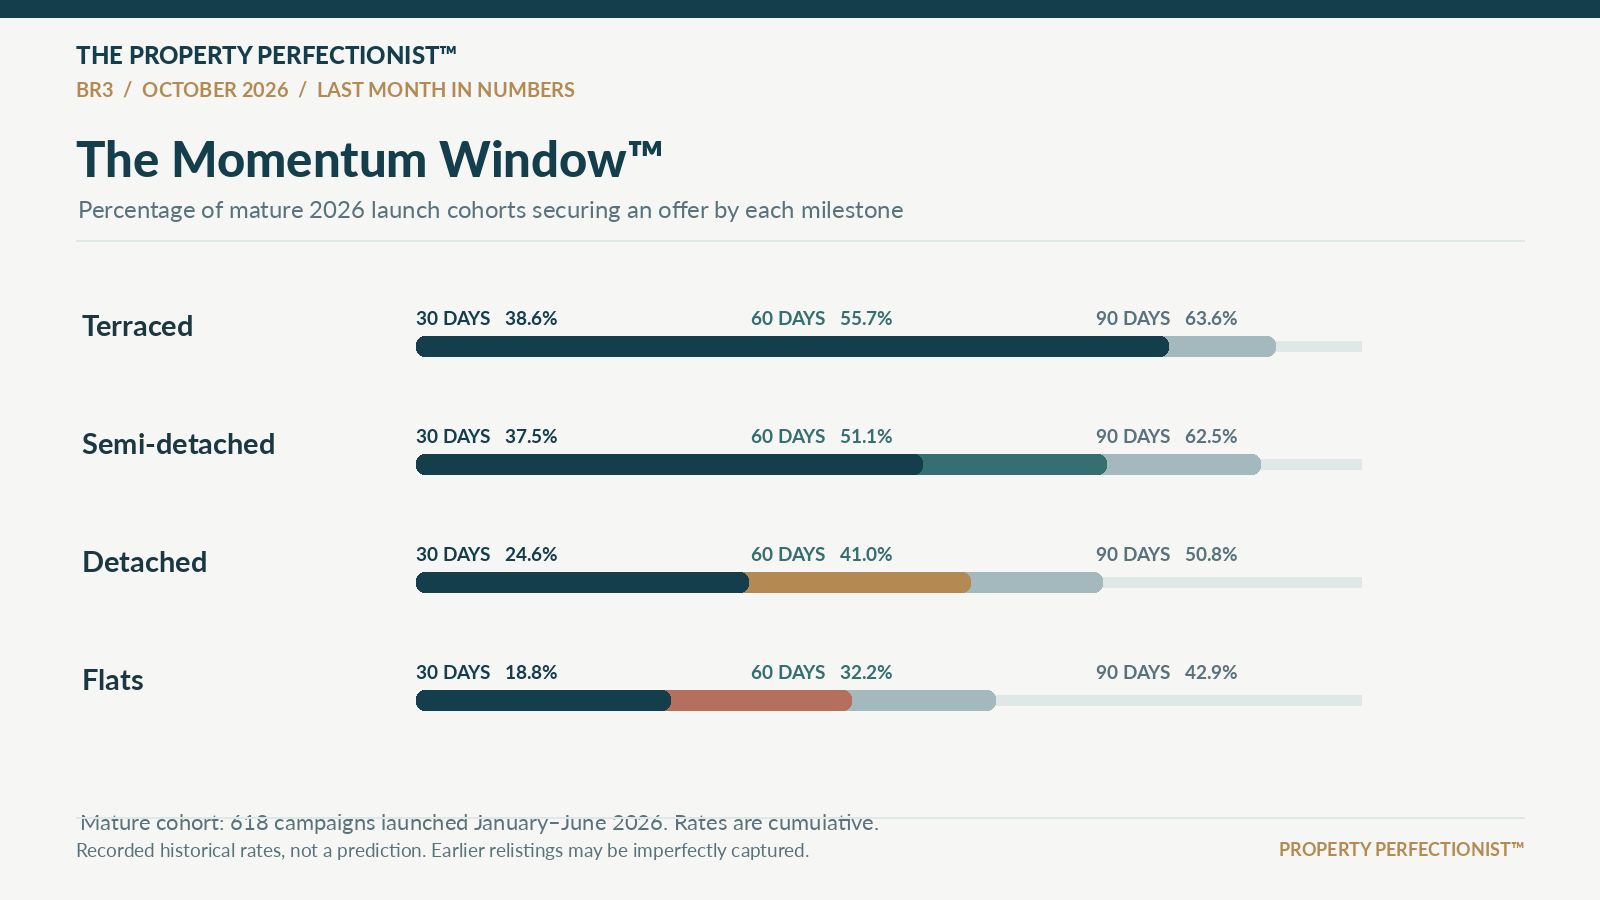
For 618 properties launched from January to June 2026, 26.5% had secured an offer within 30 days, 41.1% within 60 days and 51.1% within 90 days. The 30-day rate for terraced houses was 38.6%, compared with 18.8% for flats. Of the 316 properties that secured offers within 90 days, 254 had already done so by day 60. I call that early opportunity the Momentum Window™: the period when a well-presented, properly positioned home has the best chance of turning fresh buyer attention into viewings and offers. The figures support the importance of early engagement, though they do not prove one marketing tactic is responsible.
One postcode. Several different markets.
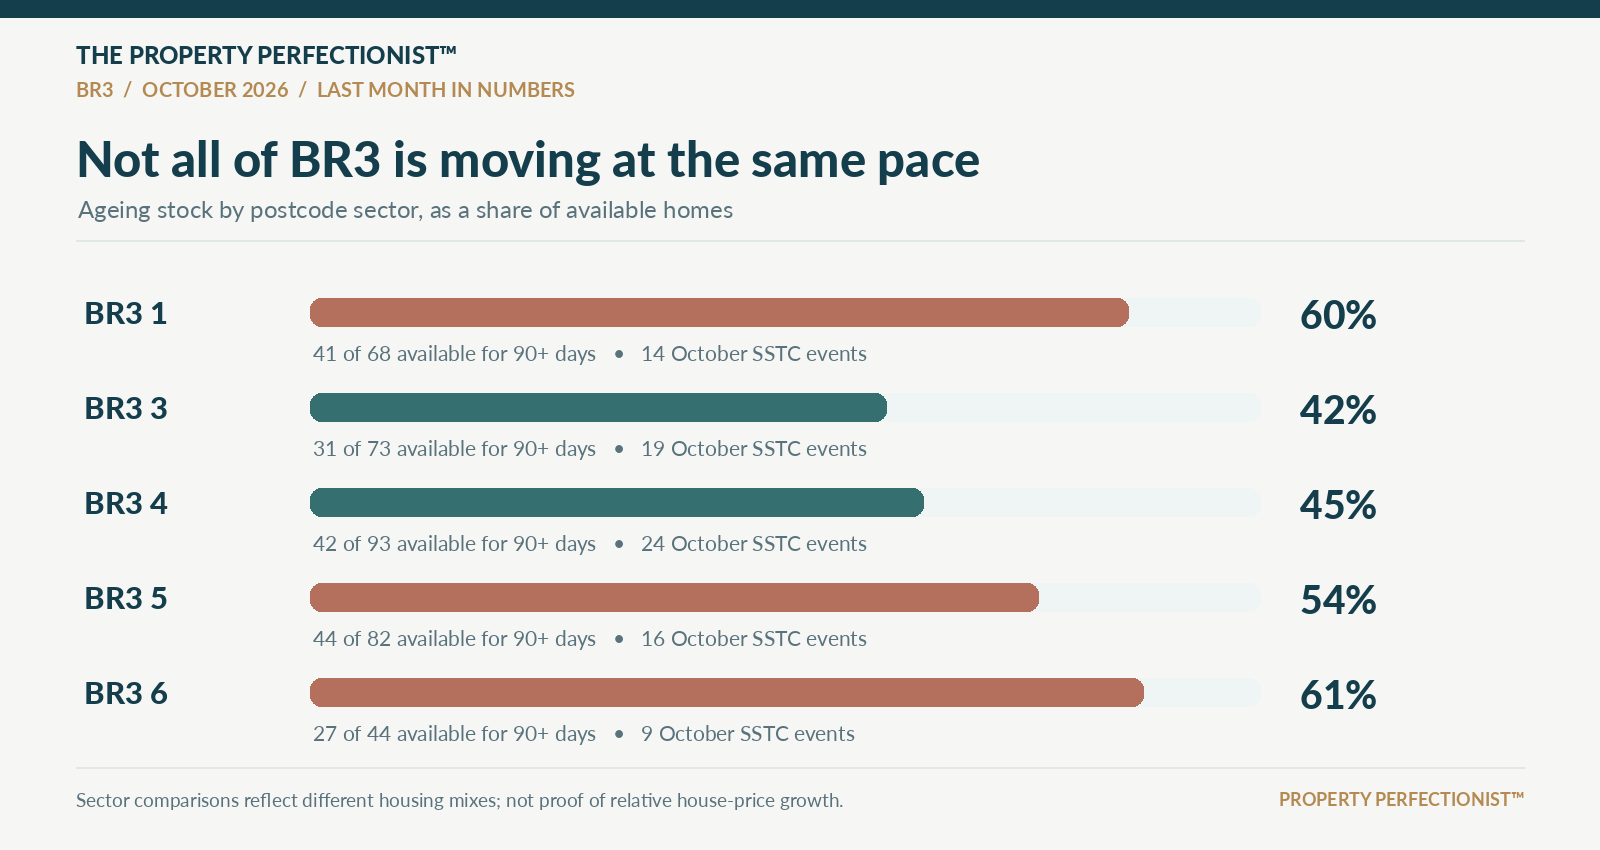
Even within BR3, the picture changes from place to place. In BR3 3, 31 of 73 available properties were older than 90 days, approximately 42%. In BR3 1 and BR3 6, the equivalent shares were about 60% and 61%. BR3 4 recorded the largest count of October offers, at 24. These comparisons are useful clues, not a postcode-sector ranking of value or price growth: the areas contain different mixes of flats, houses, ages and price points.
And what did buyers actually pay?
October 2026 Land Registry completions were not yet registered in the 4 November dataset, so I would not pretend to know the month’s achieved sale prices. The more mature April to June 2026 window contains 144 BR3 transactions: 69 flats, 37 terraced houses, 27 semis and 11 detached homes. The monthly median completed price for terraces ranged from £630,000 to £652,500 across those three months, while flats ranged from £326,000 to £374,000. Those are ranges of monthly medians, not price limits for every sale, and they serve as historical context rather than evidence of what an October offer will ultimately achieve.
My Property Perfectionist™ verdict
There is no credible single statement that “the BR3 market is strong” or “the BR3 market is weak”. Terraces are attracting buyers comparatively quickly. Flats, especially certain retirement and higher-price segments, face much more accumulated competition. The £1 million to £1.5 million detached sector has a notable volume of available stock, yet individual premium homes still attract swift offers. For any homeowner considering selling, the useful question is not just what the house down the road is asking. It is which alternatives are getting offers, how quickly, and why buyers may prefer them. That is the difference between a postcode average and a forensic market review.
Buyers decide value. Buyers compare. And every unsold property leaves clues.
If you are thinking of selling in Beckenham, Park Langley, Eden Park, Elmers End or the wider BR3 area, I offer a free Market Intelligence Report so you can see how your home sits against the current competition.
Request your FREE Market Intelligence Report:
propertyperfectionist.co.uk/market-report
Clarity. Not optimism. Not guesswork. Just evidence.
James Hall | The Property Perfectionist™
Independent Estate Agent | Powered by eXp UK
james.hall@expuk.com | 07855 828 736
Research: BR3 Sprift dataset, snapshot 4 November 2026. October launches include potential relistings; October SSTCs are not completed sales. Price cuts are changes to asking prices. October completed sale registration was not yet available. Detached band counts are incomplete.
Get the Bromley Market Briefing
Local property intelligence for Bromley and South East London, straight to your inbox. Evidence, not guesswork. Unsubscribe any time.


Leave a Reply