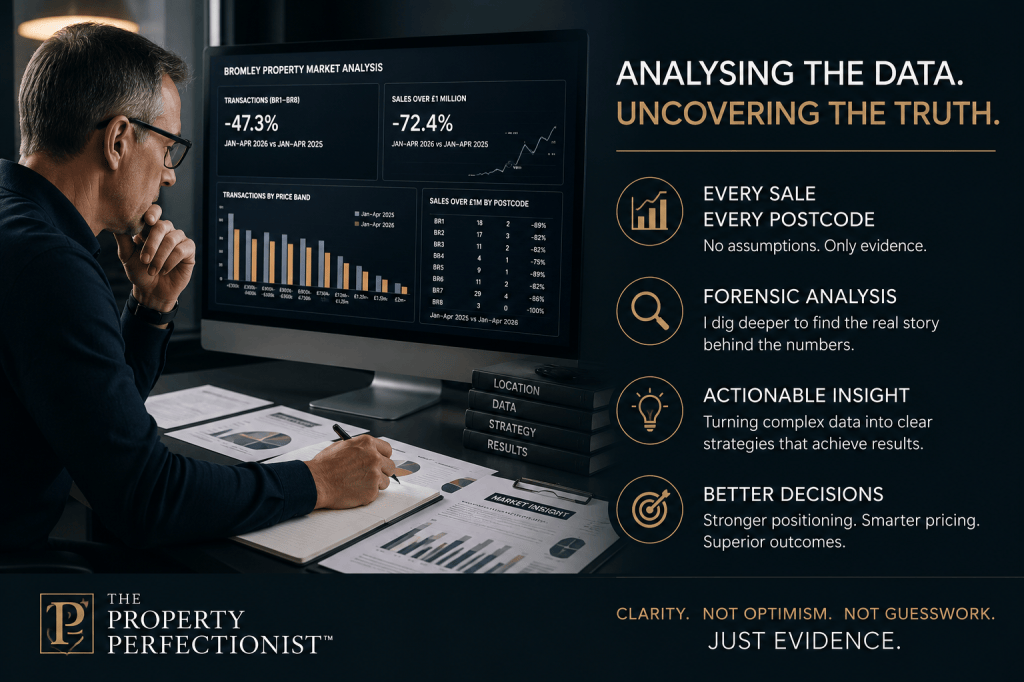
Forensic price-band analysis: BR1–BR8
I compared January–April 2025 with January–April 2026, rather than using full-year 2025 against incomplete 2026 data.
This does not measure buyer enquiries or current listings. It measures where completed transactions are appearing in Land Registry data. However, it gives us a strong indication of where buyers and sellers are still finding an acceptable price, and where agreement is becoming harder.
The overall movement
| Completed sale price | Jan–Apr 2025 | Jan–Apr 2026 | Volume change | Share change |
|---|---|---|---|---|
| Under £300k | 146 | 77 | -47.3% | No change |
| £300k–£400k | 261 | 133 | -49.0% | -0.6 pts |
| £400k–£500k | 285 | 162 | -43.2% | +1.5 pts |
| £500k–£600k | 243 | 134 | -44.9% | +0.7 pts |
| £600k–£750k | 259 | 155 | -40.2% | +2.3 pts |
| £750k–£1m | 200 | 106 | -47.0% | +0.1 pts |
| £1m–£1.25m | 54 | 12 | -77.8% | -2.1 pts |
| £1.25m–£1.5m | 35 | 14 | -60.0% | -0.6 pts |
| £1.5m–£2m | 26 | 6 | -76.9% | -1.0 pts |
| £2m+ | 12 | 3 | -75.0% | -0.4 pts |
The biggest clue
The market below £1 million has slowed, but the distribution remains relatively stable.
The severe change begins at £1 million.
- Total transactions fell by 47.3%
- Transactions below £1m fell by around 45%
- Transactions above £1m fell by 72.4%
- The £1m+ share of all completed sales fell from 8.3% to 4.4%
In other words, the upper end has not merely slowed in line with the rest of the market. It has contracted disproportionately.
Where activity is concentrating
The strongest relative concentration is now between:
£400,000 and £750,000
That part of the market accounted for:
- 51.7% of transactions in early 2025
- 56.2% in early 2026
The standout band is £600,000–£750,000, whose share increased from 17.0% to 19.3%.
This does not necessarily mean prices are rising in that band. It means a greater proportion of the homes currently completing are landing there.
That may indicate:
- stronger affordability at this level;
- more sellers willing to meet buyers;
- buyers moving down from higher budgets;
- previously £750k–£850k homes agreeing closer to the £700k range;
- a greater supply of semis and terraces, which remain more liquid than detached homes.
Detached-house buyers are moving down the ladder
The detached figures are particularly revealing.
Detached completions by price band
| Detached sale price | 2025 | 2026 | Change |
|---|---|---|---|
| £600k–£750k | 44 | 28 | -36% |
| £750k–£1m | 74 | 41 | -45% |
| £1m–£1.25m | 39 | 8 | -79% |
| £1.25m–£1.5m | 32 | 13 | -59% |
| £1.5m–£2m | 24 | 6 | -75% |
| £2m+ | 12 | 3 | -75% |
Detached sales above £1m fell from 107 to 30—a reduction of approximately 72%.
But detached sales below £1m fell by only around 40%.
That suggests the practical dividing line in today’s detached market may be around £1 million. Buyers are still transacting below it, but considerably fewer deals are being agreed above it.
What this may mean for sellers
Selling between £400k and £750k
This remains the most active part of the market.
That does not mean sellers can ask anything they like. It means there are still enough transactions to create momentum where the home is properly presented and competitively positioned.
What I would do:
Launch inside the strongest search band, rather than just above it.
For example, a home marketed at £765,000 may miss buyers searching up to £750,000. A carefully considered guide of £700,000–£750,000 could generate greater visibility and competition.
Selling between £750k and £1m
This market remains active, but transactions are down substantially.
Buyers in this bracket are likely to compare homes costing £100,000–£200,000 apart and assess the future cost of kitchens, bathrooms, extensions and energy improvements.
What I would do:
Quantify the proposition.
Show buyers:
- what has already been improved;
- what they will not need to replace;
- how the floor area compares;
- what alternatives their budget buys;
- why this home represents the stronger overall package.
Do not rely on bedrooms and square footage alone.
Selling between £1m and £1.25m
This is the band showing the steepest contraction: 54 transactions became just 12.
That is not a small movement. It suggests a genuine breakdown in liquidity.
What I would do:
I would not “test” an ambitious figure.
I would conduct a full competitor review before launch and ask:
Is this genuinely one of the strongest homes available to a buyer with £1.25 million?
If not, I would improve the presentation or reconsider the guide before going live, not after ten weeks of weak engagement.
Selling above £1.5m
Only nine transactions above £1.5m were registered across BR1–BR8 during the comparable 2026 period, versus 38 previously.
That is an extremely thin market.
At this level, a home is not competing only within its postcode. Buyers may compare Chislehurst, Beckenham, Bickley, Petts Wood, West Wickham and parts of southeast London.
What I would do:
Treat the campaign as a targeted acquisition strategy, not a standard portal listing.
That means:
- editorial-grade presentation;
- lifestyle film and narrative;
- direct contact with suitable buyers and buying agents;
- detailed documentation of improvements;
- a controlled launch;
- a guide price designed around search behaviour;
- active comparison against every credible alternative.
Postcode clues
BR7
Early 2025 recorded 29 transactions above £1m. The comparable 2026 period recorded only four.
The £1.25m–£1.5m band fell from nine sales to none, while £2m+ fell from four to none.
This is not enough evidence to say every premium Chislehurst home has lost a fixed percentage of its value. It is strong evidence that buyers and sellers are rarely agreeing at the upper end.
Seller action: Stop relying on historic peak prices. Benchmark against the best homes buyers can purchase now and build the launch around creating value relative to them.
BR3
The most significant reduction is in the £1m–£1.25m band:
- 19 sales in early 2025
- only two in early 2026
However, two £2m+ transactions did complete, showing that exceptional properties can still sell at exceptional prices.
Seller action: “Prime” is not merely a price point. A property has to look, feel and be marketed as exceptional. Average prime stock is struggling; standout stock can still transact.
BR5
Only one sale above £1m appears in the 2026 comparable data, versus nine previously.
At the same time, the greatest activity remains between £300k and £600k.
Seller action: Above £1m, ordinary local marketing is unlikely to be enough. The home needs to justify why a buyer should pay a premium over the much more liquid sub-£1m market.
BR6
BR6 appears more resilient through the £600k–£1m range:
- £600k–£750k: 36 completions
- £750k–£1m: 24 completions
But there were no recorded £1m – £1.25m completions in the period.
Seller action: Where possible, avoid positioning a property just over the £1m threshold unless the evidence clearly supports it. Crossing that line appears to produce a much smaller pool of completed buyers.
Property Perfectionist™ working theory
The data does not show buyers migrating neatly from one band to the next.
It shows a market dividing into two parts:
Below £1m: slower, but still functioning.
Above £1m: increasingly illiquid, selective and vulnerable to seller–buyer expectation gaps.
The practical message for sellers is not simply “reduce your price.”
It is:
- Identify the exact price band where buyers are still transacting.
- Understand what alternatives exist within that band.
- Make the property the strongest proposition.
- Use the asking price to increase visibility and competition.
- Do this before the listing becomes stale.


Leave a comment